Commercial Seaweed Market Global Industry Analysis and Forecast (2026-2035)

Commercial Seaweed Market size was USD 73.75 Billion in 2025, projected to reach USD 146.88 Billion by 2035, growing at a CAGR of 6.83% from 2026 to 2035. Key drivers include rising biostimulant and biofertilizer adoption in regenerative agriculture, expanding aquaculture production across Asia-Pacific, and increasing demand for seaweed-based hydrocolloids and food ingredients, with Asia-Pacific leading the market .

Download Free Sample PDF
Base Year (2025)
$73.75 Billion
Forecast (2035)
$146.88 Billion
CAGR (2026-2035)
6.8%
Top Region
Asia-Pacific

What Is the Commercial Seaweed Market Size?

The global commercial seaweed market size was valued at USD 73.75 Billion in 2025 and is estimated at USD 81.06 Billion in 2026, forecast to reach USD 146.88 Billion by 2035, expanding at a 6.83% CAGR between 2026 and 2035. Asia-Pacific leads with approximately 61% share, while Seaweed Ingredients and Derivatives dominate all other product class categories with approximately 38% share.

We observed that growth is broad-based across every segmentation axis, with hydrocolloid demand and expanding biostimulant adoption in regenerative agriculture driving the dominant structural shifts through 2035.

Commercial Seaweed Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $73.75 Billion
2025
2026 $78.79 Billion
2026
2027 $84.17 Billion
2027
2028 $89.92 Billion
2028
2029 $96.06 Billion
2029
2030 $102.62 Billion
2030
2031 $109.63 Billion
2031
2032 $117.12 Billion
2032
2033 $125.11 Billion
2033
2034 $133.66 Billion
2034
2035 $146.88 Billion
2035

Key Takeaways

By Product Class: Seaweed Ingredients and Derivatives held the largest share of approximately 38% (USD 28.03 billion) in 2025; Formulated Seaweed Products is the fastest-growing sub-segment at 8.6% CAGR from 2026–2035.

By Seaweed Material: Brown Seaweed held the largest share of approximately 46% (USD 33.93 billion) in 2025; Red Seaweed is the fastest-growing sub-segment at 7.6% CAGR from 2026–2035.

By Physical Form: Dried Whole Form held the largest share of approximately 24% (USD 17.70 billion) in 2025; Liquid Form is the fastest-growing sub-segment at approximately 8.3% CAGR from 2026–2035.

By End Use: Food and Beverage held the largest share of approximately 34% (USD 25.08 billion) in 2025; Agriculture is the fastest-growing sub-segment at approximately 8.5% CAGR from 2026–2035.

By Distribution Channel: Direct B2B held the largest share of approximately 47% (USD 34.66 billion) in 2025; Retail and Electronic Commerce is the fastest-growing sub-segment at approximately 8.9% CAGR from 2026–2035.

By Production Source: Aquaculture held the largest share of approximately 79% (USD 58.26 billion) in 2025; Aquaculture is also the fastest-growing sub-segment at approximately 7.1% CAGR from 2026–2035.

Dominant Region: Asia-Pacific dominated with approximately 61% revenue share (USD 44.99 billion) in 2025.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 8.7% during 2026–2035.

Dominant Country: China led with approximately USD 24.98 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 9.8% CAGR from 2026–2035.

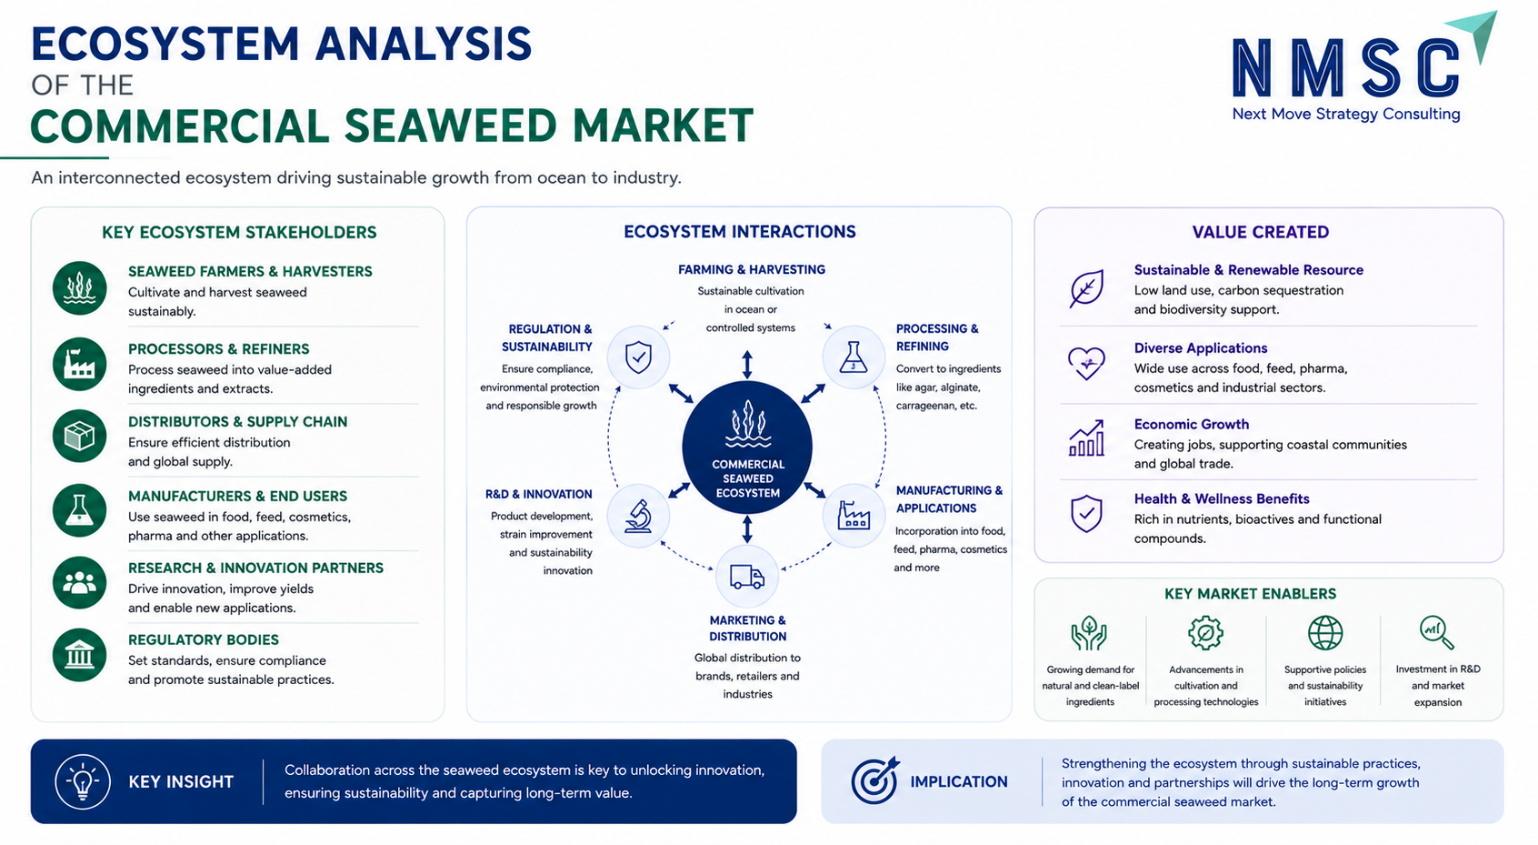
Ecosystem Analysis of the Commercial Seaweed Industry

The above infographic provides a detailed ecosystem analysis of the commercial seaweed market, outlining the interconnected roles of farmers, processors, manufacturers, and regulatory bodies. It illustrates how these stakeholders interact to transform sustainable ocean farming into diverse, value-added products for global industries. The analysis further highlights the value created, including renewable resources, economic growth, and health benefits, while identifying key enablers driving market expansion. Ultimately, it concludes that cross-ecosystem collaboration is crucial for unlocking innovation, ensuring sustainability, and capturing long-term market value .

What Does the Commercial Seaweed Market Encompass?

The commercial seaweed market encompasses the cultivation, harvesting, processing, and commercialization of macroalgae into whole seaweed products, hydrocolloid ingredients, formulated agricultural and industrial inputs, and finished food, nutraceutical, and personal care products. Our assessment indicates that the scope spans brown, red, and green seaweed species processed into alginate, carrageenan, and agar hydrocolloids, biostimulants and biofertilizers for agriculture, feed additives for animal nutrition, and edible seaweed and seasoning products serving food and beverage, pharmaceutical, and cosmetics end markets worldwide.

The market has evolved from a wild-harvest-dependent industry into an increasingly aquaculture-driven sector, with the Food and Agriculture Organization reporting that cultivation now accounts for approximately 97% of global seaweed production. We observed that technology adoption is shifting toward vertically integrated processing facilities that combine farming, extraction, and formulation capacity. NMSC's analysis indicates that this structural shift, combined with rising biostimulant demand in regenerative agriculture, is redefining commercial prioritization across the market.

Market Drivers & Dynamics

Interactive Dataset
Rising biostimulant and biofertilizer adoption in regenerative agriculture driver +1.9% North America, Europe 2026-2035
Expanding hydrocolloid demand in food and pharmaceutical applications driver +1.6% Global 2026-2035
Growing aquaculture production capacity across Asia-Pacific driver +1.3% Asia-Pacific 2026-2035
Vertically integrated processing investment reducing supply variability driver +0.9% North America, Europe 2026-2032
Rising edible seaweed and functional food product demand driver +0.7% Asia-Pacific, North America 2026-2035
Coastal water quality and climate variability affecting cultivation yields restraint -1.1% Global 2026-2035
Fragmented wild harvest supply limiting quality consistency restraint -0.8% Europe, Latin America 2026-2032
High capital cost of vertically integrated processing infrastructure restraint -0.6% Global 2026-2032
Regulatory variability across food and agricultural input approval pathways restraint -0.4% Global 2026-2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Commercial Seaweed Market?

Rising biostimulant and biofertilizer adoption in regenerative agriculture is the primary driver of the market. The Food and Agriculture Organization reports that global algae production, of which seaweed represents the overwhelming majority, reached 37.8 million tonnes in 2022, with cultivation accounting for approximately 97% of total output. We observed that this expanding cultivated feedstock base continues to support growing downstream biostimulant and biofertilizer manufacturing capacity across major agricultural markets.

How Is Aquaculture Production Expansion Driving Market Growth?

Aquaculture production expansion across Asia-Pacific is accelerating market growth by providing a scalable, consistent feedstock supply. FAO data indicates that China and Indonesia together account for the majority of global seaweed cultivation output, supporting downstream hydrocolloid and food ingredient manufacturing capacity. Our assessment indicates that this aquaculture-driven production base, combined with mechanized farming innovations from companies including Sea6 Energy, is compressing the gap between raw feedstock availability and processing capacity.

Growth Inhibitors

What Is Restraining Commercial Seaweed Market Expansion?

Coastal water quality and climate variability affecting cultivation yields restrain consistent supply growth across the industry. Seaweed farming remains highly dependent on stable coastal water temperature and quality conditions, and disruptions can meaningfully affect regional harvest volumes. We found that this environmental sensitivity, combined with fragmented aquaculture supply chains in regions still reliant on wild harvest, continues to constrain the pace of consistent, large-scale feedstock expansion outside the most mature Asian production regions.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Seaweed Ingredients and Derivatives 2025: $28.02 Billion | 2035: $51.68 Billion
Seaweed Ingr
Formulated Seaweed Products 2025: $20.65 Billion | 2035: $46.55 Billion
Formulated S
Finished Seaweed Products 2025: $14.75 Billion | 2035: $29.06 Billion
Finished Sea
Whole Seaweed 2025: $10.33 Billion | 2035: $19.59 Billion
Whole Seawee
Seaweed Ingredients and Derivatives $28.02 Billion $51.68 Billion 6.6%
Formulated Seaweed Products $20.65 Billion $46.55 Billion 8.6%
Finished Seaweed Products $14.75 Billion $29.06 Billion 7.3%
Whole Seaweed $10.33 Billion $19.59 Billion 6.9%

Which Product Class Segment Dominates the Commercial Seaweed Market?

Seaweed Ingredients and Derivatives led the market with USD 28.02 billion in 2025, reflecting sustained demand for alginate, carrageenan, and agar hydrocolloids across food, pharmaceutical, and industrial applications. We observed that Formulated Seaweed Products is the fastest-growing product class, expanding at an 8.6% CAGR from 2026 to 2035, as biostimulant and biofertilizer adoption accelerates within regenerative agriculture and companies including Acadian Seaplants and Sea6 Energy expand formulated input production capacity.

2025 (USD Billion)
2035 (USD Billion)
Brown Seaweed 2025: $33.93 Billion | 2035: $65.30 Billion
Brown Seawee
Red Seaweed 2025: $22.12 Billion | 2035: $45.32 Billion
Red Seaweed
Green Seaweed 2025: $11.80 Billion | 2035: $22.11 Billion
Green Seawee
Mixed Seaweed 2025: $4.42 Billion | 2035: $9.72 Billion
Mixed Seawee
Unspecified Seaweed 2025: $1.48 Billion | 2035: $4.43 Billion
Unspecified
Brown Seaweed $33.93 Billion $65.30 Billion 6.8%
Red Seaweed $22.12 Billion $45.32 Billion 7.6%
Green Seaweed $11.80 Billion $22.11 Billion 6.6%
Mixed Seaweed $4.42 Billion $9.72 Billion 8.4%
Unspecified Seaweed $1.48 Billion $4.43 Billion 12.5%

Which Seaweed Material Is Most Widely Processed in the Market?

Brown Seaweed remained the dominant material category across the market, reaching USD 33.93 billion in 2025 due to its role as the primary source of alginate and its widespread use in biostimulant and biofertilizer formulations. Based on research conducted by NMSC, we found that Red Seaweed is the fastest-growing material category at a 7.6% CAGR from 2026 to 2035, reflecting rising carrageenan and agar demand across food and pharmaceutical hydrocolloid applications.

2025 (USD Billion)
2035 (USD Billion)
Fresh and We
Dried Whole
Powder Form
Meal Form
Flake and Gr
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Fresh and Wet Form $10.0 USD Billion $40.0 USD Billion 12.0%
Dried Whole Form $17.1 USD Billion $51.1 USD Billion 26.0%
Powder Form $24.2 USD Billion $62.2 USD Billion 16.0%
Meal Form $31.3 USD Billion $73.3 USD Billion 14.0%
Flake and Granule Form $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Physical Form.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Food and Beverage 2025: $25.08 Billion | 2035: $46.79 Billion
Food and Bev
Agriculture 2025: $17.70 Billion | 2035: $39.93 Billion
Agriculture
Animal Nutrition 2025: $11.80 Billion | 2035: $22.28 Billion
Animal Nutri
Nutraceutical and Wellness 2025: $7.38 Billion | 2035: $15.68 Billion
Nutraceutica
Cosmetics and Personal Care 2025: $6.62 Billion | 2035: $12.98 Billion
Cosmetics an
Pharmaceutical 2025: $3.69 Billion | 2035: $6.85 Billion
Pharmaceutic
Industrial and Materials 2025: $0.74 Billion | 2035: $1.71 Billion
Industrial a
Research and Laboratory Use 2025: $0.74 Billion | 2035: $0.66 Billion
Research and
Food and Beverage $25.08 Billion $46.79 Billion 6.5%
Agriculture $17.70 Billion $39.93 Billion 8.5%
Animal Nutrition $11.80 Billion $22.28 Billion 6.9%
Nutraceutical and Wellness $7.38 Billion $15.68 Billion 7.9%
Cosmetics and Personal Care $6.62 Billion $12.98 Billion 7.1%
Pharmaceutical $3.69 Billion $6.85 Billion 6.5%
Industrial and Materials $0.74 Billion $1.71 Billion 8.9%
Research and Laboratory Use $0.74 Billion $0.66 Billion -1.2%

Which End Use Segment Leads Commercial Seaweed Market Demand?

Food and Beverage remained the leading end use within the market, valued at USD 25.08 billion in 2025 , as edible seaweed, seasonings, and hydrocolloid-based food ingredients continue to represent the largest downstream application category. Our findings suggest that Agriculture is the fastest-growing end use, registering an 8.5% CAGR from 2026 to 2035, as biostimulant and biofertilizer adoption accelerates among growers seeking regenerative, lower-synthetic-input crop nutrition solutions.

2025 (USD Billion)
2035 (USD Billion)
Direct B2B
Distributor
Retail and E
Foodservice
Other Routes
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct B2B $10.0 USD Billion $40.0 USD Billion 25.0%
Distributor and Wholesaler $17.1 USD Billion $51.1 USD Billion 19.0%
Retail and Electronic Commerce $24.2 USD Billion $62.2 USD Billion 25.0%
Foodservice $31.3 USD Billion $73.3 USD Billion 19.0%
Other Routes $38.4 USD Billion $84.4 USD Billion 20.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Distribution Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Aquaculture
Wild Harvest
Mixed or Uns
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Aquaculture $10.0 USD Billion $40.0 USD Billion 9.0%
Wild Harvest $17.1 USD Billion $51.1 USD Billion 23.0%
Mixed or Unspecified Source $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Production Source.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the commercial seaweed market over the 2026-2035 forecast period.

How Can Vertically Integrated Processing Unlock Value for North American Producers?

Vertically integrated farming-to-processing infrastructure presents a whitespace opportunity for North American producers seeking to reduce dependence on imported feedstock. Companies that replicate Cascadia Seaweed's combined cultivation and biomanufacturing model stand to capture recurring supply chain value across the Formulated Seaweed Products segment as regional buyers prioritize traceable, domestically sourced feedstock.

Where Does Mechanized Tropical Farming Create New Bioplastics Feedstock Demand?

Bioplastics and biomaterial manufacturers seeking scalable, non-petroleum feedstock represent an underpenetrated opportunity for mechanized tropical seaweed farming operations. Companies that scale production following Sea6 Energy's large-scale mechanized farming model can capture long-term supply contracts within the Industrial and Materials end-use segment as manufacturers seek alternatives to fossil-fuel-based packaging materials.

How Can Downstream Nutraceutical Integration Benefit Established Hydrocolloid Producers?

Established hydrocolloid producers expanding into downstream nutraceutical and wellness product manufacturing represent an opportunity to capture higher-margin, finished-product revenue. Early movers that integrate purified bioactive compound extraction with branded nutraceutical products can differentiate with the Nutraceutical and Wellness segment as consumer demand for marine-derived functional ingredients continues expanding through the forecast period.

Regional Outlook

Asia-Pacific $44.99 Billion $87.02 Billion 6.8%
Europe $11.06 Billion $21.34 Billion 6.8%
North America $6.64 Billion $14.02 Billion 7.8%
Middle East & Africa $5.90 Billion $13.36 Billion 8.7%
Latin America $5.16 Billion $11.14 Billion 8.0%

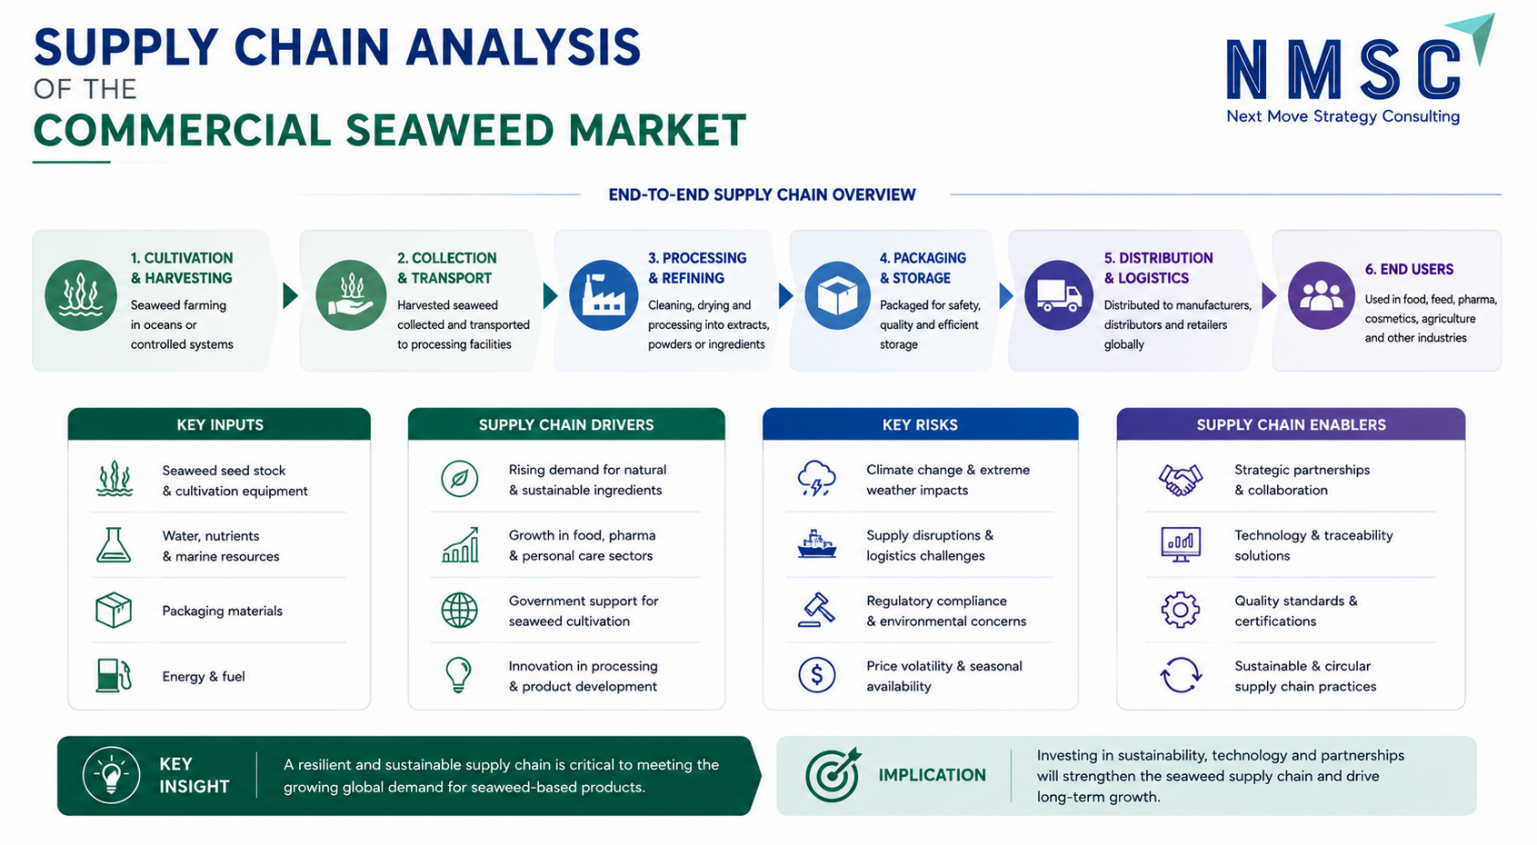
Supply Chain Analysis of the Commercial Seaweed Industry

Supply Chain Analysis of the Commercial Seaweed Industry
The above infographic provides a detailed supply chain analysis of the commercial seaweed market, tracing the end-to-end flow from cultivation and harvesting through processing and distribution to end users. It outlines key inputs, supply chain drivers, and enablers, while highlighting significant risks such as climate change and supply disruptions. The analysis further emphasizes the impact of a resilient supply chain on meeting rising global demand for seaweed-based products. Ultimately, it concludes that strategic investments in sustainability, technology, and partnerships are essential for driving long-term market growth .

Competitive Landscape

We observed that the commercial seaweed market features a moderately fragmented competitive landscape, with diversified global ingredient manufacturers competing alongside specialized hydrocolloid producers and vertically integrated seaweed farming companies across theindustry.

How Do Companies Compete in the Commercial Seaweed Market?

Companies compete primarily on production integration depth, hydrocolloid purity credentials, and formulation innovation across the industry. Diversified global manufacturers such as Cargill and Tate & Lyle leverage broad ingredient portfolios and established food industry relationships, while specialized hydrocolloid producers including KIMICA and Gelymar compete on purity and consistency for pharmaceutical and food-grade applications.

Which Competitive Archetypes Dominate the Commercial Seaweed Market?

Two archetypes dominate the market: diversified global ingredient manufacturers offering seaweed derivatives alongside broader specialty chemical and food ingredient portfolios, and vertically integrated seaweed-focused producers controlling cultivation through processing. Cargill and Tate & Lyle exemplify the diversified archetype, while Cascadia Seaweed and Sea6 Energy exemplify the vertically integrated archetype pursuing direct control over feedstock quality and supply consistency.

How Are Companies Differentiating Through Innovation in Commercial Seaweed?

Innovation and differentiation strategy increasingly center on vertically integrated production infrastructure and mechanized farming technology. Cascadia Seaweed's Port Edward biomanufacturing facility and Sea6 Energy's mechanized tropical farming model both illustrate how producers are investing in direct production control rather than relying solely on third-party feedstock procurement. Our analysis shows that producers unable to demonstrate traceable, integrated supply chains risk losing differentiation against vertically capable competitors as buyers increasingly prioritize supply chain transparency.

What M&A and Expansion Activity Is Shaping the Commercial Seaweed Market?

Acquisition and capacity expansion activity continue to consolidate the market's processing base. Acadian Seaplants ' acquisition of a European seaweed processor and Sea6 Energy's acquisition of a regional seaweed farming company both illustrate how established producers acquire complementary capacity rather than relying solely on organic capacity build-out, while Cascadia Seaweed's government-supported Port Edward facility demonstrates an alternative, infrastructure-led expansion strategy.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, production capacity, and commercial strategy within the global commercial seaweed market.

KIMICA Corporation Compañía Española de Algas Marinas S.A. Qingdao Bright Moon Seaweed Group Co., Ltd. Gelymar S.A. Qingdao Gather Great Ocean Algae Industry Group Co., Ltd. Roquette Frères S.A. Tate & Lyle PLC International Flavors & Fragrances Inc. Acadian Seaplants Limited Algaia S.A. Cargill, Incorporated Seasol International Pty Ltd Sea6 Energy Pvt. Ltd. BioAtlantis Ltd. Groupe Roullier Beijing Leili Agricultural Co., Ltd. BRANDT Consolidated, Inc. The Seaweed Company B.V. Ocean Rainforest Sp /f Cascadia Seaweed Corporation

Latest Developments

We found that recent developments within the commercial seaweed market are concentrated on vertically integrated processing capacity launches and targeted acquisitions, reflecting the industry's continued production consolidation.

Date Event
June 2025 SȾÁUTW̱ became a shareholder of Cascadia Seaweed, deepening First Nations participation in the company's marine operations. Cascadia subsequently reported its largest harvest at the site in May 2025, exceeding 150 wet tonnes of cultivated seaweed .
February 2025 Ocean Rainforest acquired a 60% stake in Mexico-based Alamarsa , owner of the Algamar brand, which produces biostimulants and food products from giant kelp and other seaweed species.

Expert Insights

Karen Scofield Seal

Karen Scofield Seal

CEO and Co-founder | Oceanium

"“ Seaweed’s like the next soy. 20 years ago no one had heard of it; now it’s in your fridge, in your makeup, in your cosmetics, it’s permeated throughout many industries . ”"

Analyst Interpretation

Thestatement highlights the accelerating commercial diversification of seaweed beyond traditional food applications, with its functional and sustainability attributes supporting adoption across food, cosmetics, agriculture, packaging, and other industrial value chains. Next Move Strategy Consulting’s analysis indicates that the expansion of downstream applications is strengthening demand for cultivated seaweed and value-added derivatives such as hydrocolloids, extracts, and bioactive compounds. Our findings suggest that broader industrial integration will remain a key growth catalyst for the commercial seaweed market as manufacturers increasingly develop seaweed-based alternatives to conventional ingredients and materials .

Investment Opportunities

What Capital Inflows Are Targeting the Commercial Seaweed Market?

Capital inflows into the commercial seaweed market are increasingly directed toward vertically integrated processing infrastructure and downstream capacity expansion. Acadian Seaplants ' acquisition of a European seaweed processor and Sea6 Energy's acquisition of a regional farming company both illustrate continued strategic capital deployment toward capability expansion. We observed that investors favor producers demonstrating validated, scalable integrated production models over fragmented, wild-harvest-dependent supply chains.

How Is Infrastructure Investment Supporting Commercial Seaweed Production?

Infrastructure investment is expanding vertically integrated cultivation and processing capacity among leading producers. Cascadia Seaweed's Port Edward, British Columbia facility, supported by a CAD 2,634,977.76 National Research Council of Canada funding agreement, exemplifies government-backed infrastructure investment targeting large-scale ocean farming and cost-effective processing technology. This scale of investment supports producers' transition from feedstock procurement toward direct production control.

What ESG Considerations Are Shaping Commercial Seaweed Investment Decisions?

Environmental, social, and governance considerations in the commercial seaweed market center on seaweed's role as a low-input, ocean-based biomass source requiring no land, freshwater, or synthetic fertilizer inputs. Sea6 Energy's mechanized tropical farming model exemplifies how sustainable aquaculture production supports climate-linked biofuel and bioplastics feedstock development without competing with terrestrial agriculture. We found that investors increasingly favor producers demonstrating verifiable environmental benefit alongside commercial scalability.

Key Benefits for Stakeholders

How Does This Report Benefit Agriculture and Food Industry Leaders?

Agriculture and food industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and product development decisions across the commercial seaweed industry. Our analysis shows that detailed product class, seaweed material, and end use breakdowns help procurement teams align ingredient sourcing with hydrocolloid purity requirements and biostimulant formulation needs while identifying underserved segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the commercial seaweed supply chain. We observed that the report's regional and segment-level growth differentials help identify which producers and geographies are best positioned to capture above-market growth in agriculture and Middle East & Africa categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including mechanized farming technology, vertically integrated processing architecture, and formulated biostimulant innovation, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around validated cultivation efficiency and processing cost reduction increasingly required by commercial producer procurement processes.

Key Market Segments Evaluated

By Product Class

  • Seaweed Ingredients and Derivatives
  • Formulated Seaweed Products
  • Finished Seaweed Products
  • Whole Seaweed

By Seaweed Material

  • Brown Seaweed
  • Red Seaweed
  • Green Seaweed
  • Mixed Seaweed
  • Unspecified Seaweed

By Physical Form

  • Fresh and Wet Form
  • Dried Whole Form
  • Powder Form
  • Meal Form
  • Flake and Granule Form
  • Liquid Form
  • Dry Ingredient Form
  • Capsule and Tablet Form
  • Sheet and Film Form
  • Other Finished Form

By End Use

  • Food and Beverage
  • Agriculture
  • Animal Nutrition
  • Nutraceutical and Wellness
  • Cosmetics and Personal Care
  • Pharmaceutical
  • Industrial and Materials
  • Research and Laboratory Use

By Distribution Channel

  • Direct B2B
  • Distributor and Wholesaler
  • Retail and Electronic Commerce
  • Foodservice
  • Other Routes

By Production Source

  • Aquaculture
  • Wild Harvest
  • Mixed or Unspecified Source

Conclusion & Recommendations

The long-term outlook for the market remains steady and positive, with global revenue projected to expand from USD 73.75 Billion in 2025 to USD 146.88 Billion by 2035 at a 6.83% CAGR. We observed that rising biostimulant adoption in regenerative agriculture, expanding hydrocolloid demand, and continued aquaculture production growth across Asia-Pacific will continue underpinning demand across Seaweed Ingredients and Derivatives and Formulated Seaweed Products categories through the forecast period.

What Strategic Positioning Should Commercial Seaweed Companies Pursue?

Companies should prioritize vertically integrated cultivation-to-processing infrastructure and formulation innovation to secure long-term supply chain resilience. Our assessment indicates that producers investing early in mechanized farming technology and validated, traceable supply chains will be best positioned to capture premium pricing within the commercial seaweed market as buyers increasingly prioritize supply chain transparency.

How Attractive Is the Commercial Seaweed Market for New Investment?

The commercial seaweed industry presents an attractive investment case, supported by a USD 65.82 Billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Middle East & Africa and Formulated Seaweed Products categories. We found that investment attractiveness is highest for companies combining vertically integrated production capability with diversified, multi-end-use product portfolios, positioning them to serve both mature food ingredient and emerging agricultural input markets simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor coastal water quality and climate variability affecting cultivation yields, fragmented wild harvest supply limiting quality consistency, and high capital costs for vertically integrated processing infrastructure as key risks to the commercial seaweed market. Our analysis shows that producers unable to secure consistent, climate-resilient feedstock supply risk losing market share to competitors with more diversified or better-managed cultivation operations.

What Are the Key Growth Pathways for the Commercial Seaweed Market?

Key growth pathways include expanding vertically integrated processing infrastructure, scaling mechanized tropical farming technology, and deepening penetration into agriculture and Middle East & Africa markets. NMSC's analysis indicates that companies pursuing these pathways while maintaining consistent, traceable feedstock supply will be best positioned to capture the commercial seaweed market's projected growth through 2035.

FAQs

About the Author

Sikha Haritwal

Sikha Haritwal

Sikha Haritwal is an assistant manager with strong expertise in market research, data analysis, and cross-functional coordination. She plays a key role in leading complex research initiatives, strengthening analytical rigor, and enabling data-driven decision-making across teams. Known for her leadership mindset and structured problem-solving approach, she supports process improvement, enhances operational efficiency, and contributes to building scalable frameworks that drive long-term strategic outcomes and organizational effectiveness.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖