Orthodontics Market

Orthodontics Market size was USD 24.29 Billion in 2025, projected to reach USD 72.70 Billion by 2035, growing at a CAGR of 10.7% from 2026 to 2035. Key drivers include rising adult orthodontic treatment adoption, expanding clinical indications for clear aligner therapy, and the expansion of digital orthodontic platforms and integrated workflows, with North America leading the market .

Download Free Sample PDF
Base Year (2025)
$24.29 Billion
Forecast (2035)
$72.70 Billion
CAGR (2026-2035)
10.7%
Top Country
North America

What Is the Orthodontics Market Size?

The global Orthodontics Market size reached USD 24.29 Billion in 2025 and is estimated at USD 29.13 Billion in 2026, forecast to reach USD 72.70 Billion by 2035 at a CAGR of 10.7% between 2026 and 2035. North America leads with an approximate 42% share, while Orthodontic Products dominate the offering segment at approximately 74% share in 2025.

We observed that adult treatment demand is scaling alongside continued teen and child volume, a shift reinforced by dental service organization consolidation that is pulling digital orthodontic software and services revenue ahead of the broader market even as physical products remain the largest overall revenue base.

Orthodontics Market Revenue Forecast

Values in USD Billion

2025 $24.29 Billion
2025
2026 $29.13 Billion
2026
2027 $32.25 Billion
2027
2028 $35.70 Billion
2028
2029 $39.52 Billion
2029
2030 $43.75 Billion
2030
2031 $48.43 Billion
2031
2032 $53.61 Billion
2032
2033 $59.34 Billion
2033
2034 $65.69 Billion
2034
2035 $72.70 Billion
2035

Key Takeaways

By Offering: Orthodontic Products held the largest share, expanding from USD 17.98 billion in 2025 to USD 47.98 billion by 2035; Orthodontic Digital Solutions is the fastest-growing sub-segment at 15.17% CAGR from 2026–2035.

By Customer Type: Orthodontists held the largest share, expanding from USD 10.20 billion in 2025 to USD 26.18 billion by 2035; Direct Consumer is the fastest-growing sub-segment at 15.74% CAGR from 2026–2035.

By Patient Cohort: Adults held the largest share, expanding from USD 11.17 billion in 2025 to USD 34.90 billion by 2035; Adults are also the fastest-growing sub-segment at 11.22% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 42% revenue share in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 13.18% during 2026–2035.

Dominant Country: The U.S. led the market, anchored by concentrated Invisalign adoption and high orthodontist density.

Fastest-Growing Country: India is the fastest-growing country, supported by rising disposable income and expanding access to orthodontic clinics.

The market presents an absolute investment opportunity of approximately USD 43.57 Billion between 2026 and 2035, calculated as the difference between the 2035 forecast of USD 72.70 Billion and the 2026 base of USD 29.13 Billion, positioning clear aligner and digital orthodontic platforms as a high-conviction category for dental device manufacturers and DSO investors.

According to NMSC analysis, the segment's momentum stems from the convergence of adult aesthetic treatment demand with digital workflow platforms that integrate scanning, treatment planning, and remote monitoring, which is expanding total addressable spend per case well beyond traditional bracket-and-wire pricing.

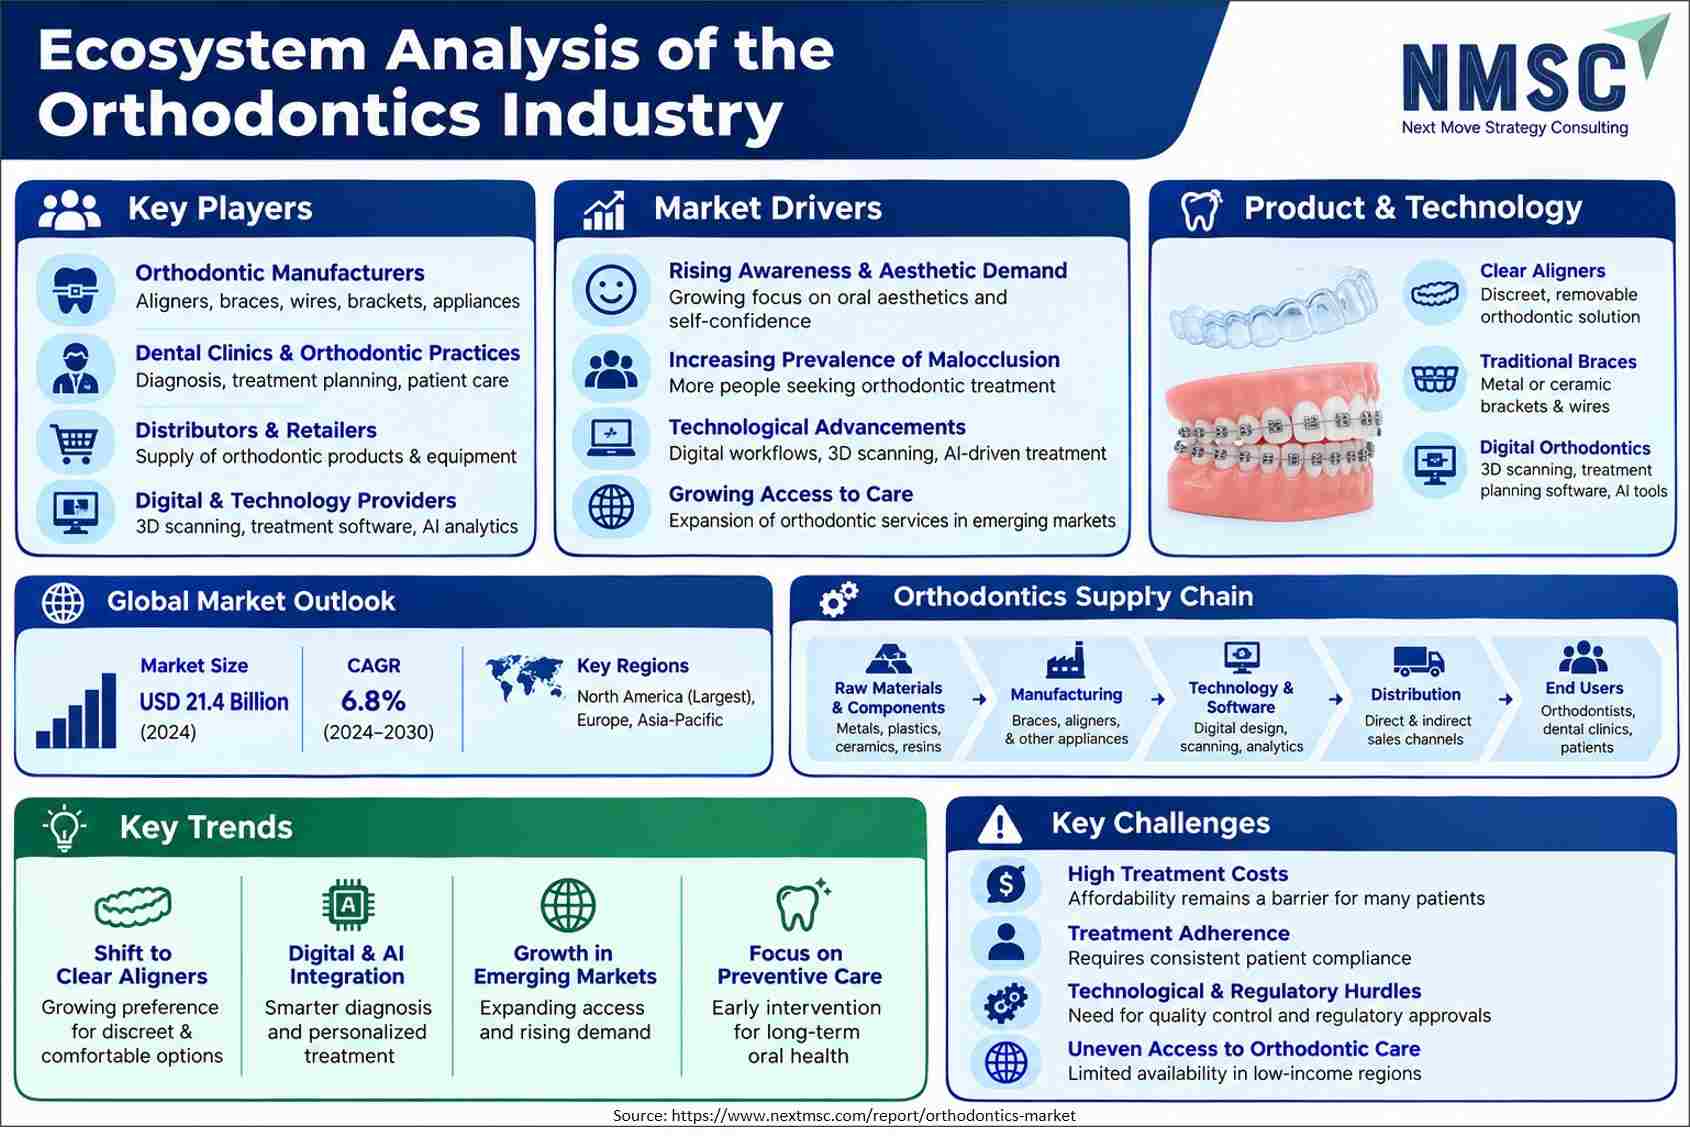
Ecosystem Analysis of the OrthodonticsIndustry

The above infographic provides a detailed ecosystem analysis of the orthodontics market , mapping its key players, market drivers, and supply chain alongside global market outlooks. It highlights significant trends like the shift toward clear aligners and AI integration, while identifying major challenges such as high treatment costs and uneven access. Overall , the diagram underscores how technological innovation and evolving consumer demands are reshaping orthodontic care worldwide .

What does the Orthodontics Market Encompass?

The Orthodontics Market covers clear aligners, retention appliances, fixed appliances, bonding products, and instruments alongside treatment planning, case design, and remote monitoring software , as well as orthodontic laboratory, contract manufacturing, and practice support services delivered to orthodontists, general dentists, dental service organizations, and direct consumers. We observed that the market has evolved from a bracket-and-wire-centric specialty into a digitally integrated discipline where scanning, AI-assisted treatment planning, and remote monitoring increasingly determine case volume and patient retention.
Our findings suggest that dental service organization consolidation is structurally reshaping purchasing patterns, as centralized DSO procurement increasingly favors vendors offering integrated digital platforms over single-product suppliers. Technology adoption trends toward direct 3D printing of aligners and appliances are further compressing production timelines relative to traditional thermoforming and conventional manufacturing methods across both branded and private label commercial models.

Market Drivers & Dynamics

Interactive Dataset
Rising adult orthodontic treatment adoption driver +3.4% North America, Europe 2026–2035
Expanding clear aligner clinical indication breadth driver +2.6% Global 2026–2032
Dental service organization consolidation and centralized procurement driver +2.1% North America, Europe 2026–2033
Growth of digital treatment planning and remote monitoring platforms driver +1.7% North America, Asia-Pacific 2026–2031
Rising disposable income and orthodontic access in Asia-Pacific driver +1.3% Asia-Pacific, Latin America 2026–2035
High out-of-pocket cost limiting adoption in emerging markets restraint −1.4% Asia-Pacific, MEA, Latin America 2026–2035
Direct-to-consumer aligner safety and oversight concerns restraint −0.9% North America, Europe 2026–2030
Reimbursement limitations for adult orthodontic treatment restraint −0.7% Global 2026–2032
Orthodontist workforce capacity constraints in underserved regions restraint −0.5% Asia-Pacific, MEA 2026–2031
Source: Next Move Strategy Consulting

Growth Drivers

What is the Primary Growth Driver in the Orthodontics Market ?

The primary growth driver is rising adult orthodontic treatment adoption combined with expanding clinical indication breadth for clear aligner therapy. Align Technology reported full-year 2025 total revenues of a record USD 4.0 billion, with Clear Aligner revenues of USD 3.2 billion, evidencing sustained enterprise-scale demand across an increasingly diverse patient population beyond the historically teen-dominant case base.

How is Digital Platform Expansion Driving the Orthodontics Market Growth?
Our analysis shows that digital platform expansion is directly driving market growth, with Align Technology reporting Systems and Services revenues of USD 789.6 million in fiscal 2025, up 2.7% year-over-year, driven by continued iTero Lumina scanner sales that represented approximately 86% of full systems units sold in the fourth quarter. This sustained scanner and software adoption evidences durable demand for integrated digital workflows across orthodontic and restorative practices.

Growth Inhibitors

What is Restraining the Orthodontics Market?

We found that the primary restraint is high out-of-pocket treatment cost, which limits adoption among price-sensitive patients in emerging markets where dental insurance coverage for orthodontic treatment remains limited. Industry-derived estimates suggest that orthodontist workforce capacity constraints in underserved regions are also slowing broader clinical adoption relative to patient demand growth in Asia-Pacific and Middle East & Africa markets.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Orthodontic
Clear Aligne
Full Treatme
Limited Trea
Refinement A
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Orthodontic Products $10.0 USD Billion $40.0 USD Billion 14.0%
Clear Aligners $17.1 USD Billion $51.1 USD Billion 8.0%
Full Treatment Aligners $24.2 USD Billion $62.2 USD Billion 14.0%
Limited Treatment Aligners $31.3 USD Billion $73.3 USD Billion 20.0%
Refinement Aligners $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Offering.

Unlock Full Data

Which Offering Segment Dominates the Orthodontics Market ?

Orthodontic Products lead with USD 17.98 Billion in 2025, expanding to USD 47.98 Billion by 2035, reflecting the continued centrality of clear aligners, fixed appliances, and bonding products to overall case value. Orthodontic Digital Solutions is the fastest-growing offering segment at a 15.17% CAGR, as treatment planning, remote monitoring, and patient engagement software increasingly become embedded within standard case workflows rather than optional add-ons.

2025 (USD Billion)
2035 (USD Billion)
Orthodontist
General Dent
Dental Servi
Clinic and H
Dental Labor
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Orthodontist $10.0 USD Billion $40.0 USD Billion 25.0%
General Dentist $17.1 USD Billion $51.1 USD Billion 11.0%
Dental Service Organization $24.2 USD Billion $62.2 USD Billion 25.0%
Clinic and Hospital $31.3 USD Billion $73.3 USD Billion 11.0%
Dental Laboratory $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Customer Type.

Unlock Full Data

Which Customer Type Leads and Which Grows Fastest?

Orthodontist customers dominate at USD 10.20 Billion in 2025, reflecting their role as the primary clinical decision-makers for the majority of complex orthodontic cases. Direct Consumer is the fastest-growing customer type at a 15.74% CAGR, as teledentistry-enabled direct-to-consumer clear aligner models continue expanding access for mild-to-moderate cases that do not require in-person orthodontist oversight throughout treatment.

2025 (USD Billion)
2035 (USD Billion)
Child
Teen
Adult
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Child $10.0 USD Billion $40.0 USD Billion 21.0%
Teen $17.1 USD Billion $51.1 USD Billion 23.0%
Adult $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Patient Cohort.

Unlock Full Data

Which Patient Cohort Dominates and Which is Fastest-Growing?

Adult patients lead cohort demand at USD 11.17 Billion in 2025, growing to USD 34.90 Billion by 2035, reflecting increasing willingness among working-age adults to pursue aesthetic and functional orthodontic treatment. Adults are also the fastest-growing patient cohort at an 11.22% CAGR, as clear aligner discretion and shorter treatment protocols continue lowering barriers to adult treatment initiation relative to traditional fixed appliance therapy.

2025 (USD Billion)
2035 (USD Billion)
Direct Sales
Distributor
E-Commerce C
Laboratory C
Direct to Co
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Sales $10.0 USD Billion $40.0 USD Billion 27.0%
Distributor Channel $17.1 USD Billion $51.1 USD Billion 9.0%
E-Commerce Channel $24.2 USD Billion $62.2 USD Billion 19.0%
Laboratory Channel $31.3 USD Billion $73.3 USD Billion 17.0%
Direct to Consumer Platform $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Branded Mode
OEM Model
Private Labe
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Branded Model $10.0 USD Billion $40.0 USD Billion 14.0%
OEM Model $17.1 USD Billion $51.1 USD Billion 24.0%
Private Label Model $24.2 USD Billion $62.2 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Commercial Model.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Diagnosis an
Active Treat
Retention St
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Diagnosis and Planning $10.0 USD Billion $40.0 USD Billion 24.0%
Active Treatment $17.1 USD Billion $51.1 USD Billion 22.0%
Retention Stage $24.2 USD Billion $62.2 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Treatment Stage.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Thermoformin
Direct Print
Conventional
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Thermoforming $10.0 USD Billion $40.0 USD Billion 23.0%
Direct Printing $17.1 USD Billion $51.1 USD Billion 9.0%
Conventional Manufacturing $24.2 USD Billion $62.2 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Manufacturing Technology.

Unlock Full Data

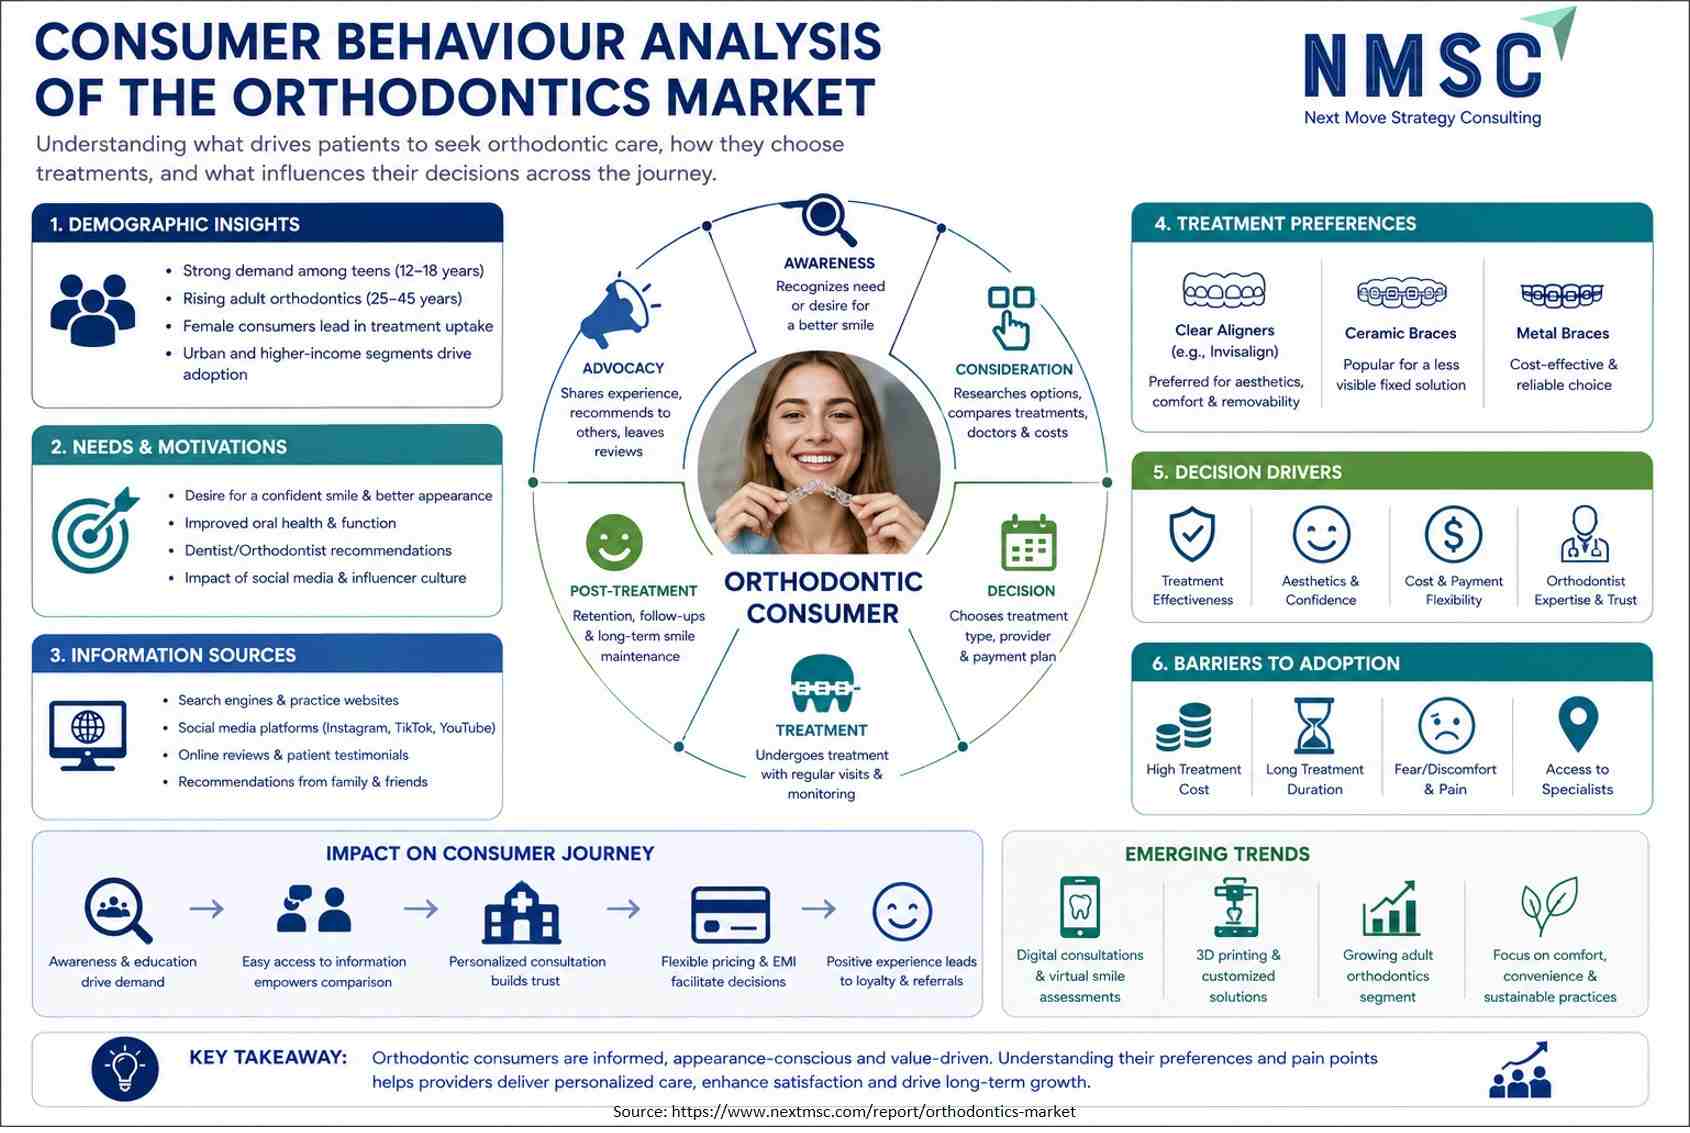
Consumer Behaviour Analysis of the OrthodonticsIndustry

The above infographic provides a detailed analysis of consumer behavior within the orthodontics market, examining the demographics, motivations, and information sources that shape patient decisions. It visualizes the consumer's journey from awareness to advocacy, highlighting specific treatment preferences and key decision drivers. Furthermore, the diagram identifies major barriers to adoption and emerging trends, concluding that understanding patient preferences and pain points is essential for providers to deliver personalized care and drive long-term growth .

Growth Opportunities

Our analysis shows that three whitespace opportunities stand out for manufacturers and service providers positioning ahead of 2035 demand.

Can Expanded Class II Treatment Indications Unlock New Patient Volume?

Manufacturers that expand clear aligner clinical indications for complex malocclusion cases, including Class II mandibular retrusion treatment, can capture patient volume previously limited to fixed appliance therapy alone, benefiting the Orthodontic Products segment as indication breadth continues to widen.

Does DSO-Focused Digital Platform Bundling Create Value for Multi-Location Practices?

Vendors that bundle scanning, treatment planning, and practice management software into unified DSO-focused platforms can capture rising centralized procurement demand, benefiting the Orthodontic Digital Solutions segment and Dental Service Organization customer type as multi-location practices consolidate vendor relationships.

Can Teledentistry-Enabled Direct Consumer Models Expand Access in Underserved Markets?

Companies offering remote-monitored, teledentistry-enabled direct-to-consumer treatment models can capture rising demand from patients in regions with limited orthodontist access, benefiting the Direct Consumer customer type as remote monitoring software matures to support safe, effective self-directed treatment for appropriate cases.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Latin Americ
Middle East
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Latin America $31.3 USD Billion $73.3 USD Billion 23.0%
Middle East & Africa $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our assessment indicates that the competitive landscape spans diversified digital orthodontics platform leaders, specialized fixed appliance manufacturers, and regional laboratory and services providers, each competing on clinical indication breadth, digital workflow integration, and DSO account depth. Key Takeaways Dimension | Assessment Market Structure | Moderately consolidated; top 10 companies hold the majority of Market Share, led by an integrated digital platform leader alongside established fixed appliance and laboratory specialists Innovation Focus | Expanded clear aligner clinical indications, integrated scanning and CAD/CAM platforms, AI-assisted treatment planning, and DSO-focused digital bundling M&A Activity | Selective capability acquisitions and platform integration rather than large-scale consolidation among established manufacturers Source: www.nextmsc.com

Dimension Description
Market Structure Moderately consolidated; top 10 companies hold the majority of Market Share, led by an integrated digital platform leader alongside established fixed appliance and laboratory specialists
Innovation Focus Expanded clear aligner clinical indications, integrated scanning and CAD/CAM platforms, AI-assisted treatment planning, and DSO-focused digital bundling
M&A Activity Selective capability acquisitions and platform integration rather than large-scale consolidation among established manufacturers

How Do Companies Compete in the Orthodontics Market Industry?

Companies compete primarily on clinical indication breadth for clear aligner and fixed appliance therapy, depth of digital workflow integration across scanning, planning, and monitoring, and strength of DSO and multi-location practice relationships. Our findings suggest that vendors with integrated hardware-software ecosystems hold a structural advantage over single-product competitors, since practices increasingly favor consolidated vendor relationships over fragmented point solutions.

Which Competitive Archetypes Dominate the Orthodontics Market Industry?

Diversified digital platform leaders such as Align Technology dominate through integrated clear aligner, scanning, and CAD/CAM ecosystems spanning multiple offering categories, while specialized fixed appliance manufacturers including Ormco, American Orthodontics, and Dentaurum differentiate through focused bracket and archwire engineering expertise. Regional laboratory and services providers such as Great Lakes Dental Technologies compete on localized manufacturing and practice support relationships underserved by global platform vendors.

What Innovation and Differentiation Strategies Are Companies Pursuing?

We observed that leading companies are investing in expanded clinical indications and AI-assisted digital treatment planning to capture population beyond traditional teen-centric case volume. Differentiation increasingly rests on integrated digital ecosystem breadth, since practices and DSOs increasingly evaluate vendors on end-to-end workflow capability rather than individual product performance alone.

What M&A and Partnership Activity Is Shaping the Orthodontics Market ?

Recent activity favors organic clinical indication expansion and digital platform enhancement over large-scale acquisitions, exemplified by Align Technology's July 2025 launch of its mandibular advancement clear aligner system and continued iTero Lumina scanner adoption. Our analysis shows that established manufacturers are prioritizing internal innovation investment over M&A, reflecting the clinical validation intensity required for new orthodontic treatment indications.

Key Market Players

Based on research conducted by NMSC, the following companies represent the validated set of leading participants across orthodontic products, digital solutions, and services.

Align Technology, Inc. Angelalign Technology Inc. Ormco Corporation ClearCorrect Operating, LLC American Orthodontics Corporation Dental Morelli Ltda. Dentaurum GmbH & Co. KG TP Orthodontics, Inc. FORESTADENT Bernhard Förster GmbH G&H Orthodontics, LLC Leone S.p.A. DB Orthodontics Limited OrthoAmerica Holdings, LLC Smartee Denti-Technology Co., Ltd. DynaFlex Great Lakes Dental Technologies GC Orthodontics Europe GmbH Reliance Orthodontic Products, Inc. Orthometric Indústria e Comércio de Produtos Médicos e Odontológicos Ltda. DENTOS Inc.

Latest Developments

We found that recent corporate activity reflects continued clinical indication expansion and sustained digital platform revenue growth even as the overall competitive landscape remains concentrated among established manufacturers in the Orthodontics Market .

Date Event
May 2026 Align Technology announced plans for a new manufacturing facility in Hyderabad to support its Invisalign clear-aligner business. The approximately USD 200 million investment will expand orthodontic manufacturing capacity in India and strengthen supply capabilities for the company’s growing clear-aligner and digital orthodontics operations across Asia-Pacific.
October 2025 Straumann announced strategic partnerships involving ClearCorrect, Smartee, and DentalMonitoring to strengthen its orthodontics business. The initiative combines clear-aligner manufacturing, AI-supported remote monitoring, and treatment-management capabilities, while ClearCorrect planned broader deployment of RemoteCare for digitally managed orthodontic treatments.
July 2025 Align Technology introduced commercial availability in India of its Invisalign system with mandibular advancement featuring occlusal blocks. The orthodontic solution is designed for growing patients requiring Class II correction while simultaneously moving teeth, extending Invisalign’s clear-aligner capabilities into more complex orthodontic treatment applications.
March 2025 Eon Dental partnered with GC Orthodontics to launch the co-branded MOV’Aligners clear-aligner system. The collaboration adds clear-aligner treatment to GC Orthodontics’ existing orthodontic portfolio, allowing the company to address both conventional orthodontic treatment and digitally planned clear-aligner treatment through an expanded product offering.
March 2025 FORESTADENT introduced its FAS Aligner System, integrating CBCT scans and rotational movement recordings of the lower jaw into orthodontic treatment planning. The system incorporates information on tooth-root positioning, bone structure, and jaw functionality to support individualized and digitally planned clear-aligner treatment.

Expert Insights

Amir Mansouri

Amir Mansouri

CEO and Co-Founder | SprintRay

" The orthodontic community is one of the fastest adopters of 3-D printing technology, transforming highly manual processes into digital, repeatable workflows . "

Analyst Interpretation

We observed that this executive perspective aligns closely with our analysis of the Orthodontics Market, where the adoption of digital workflows is reshaping orthodontic treatment planning, appliance manufacturing, and chairside delivery. Our analysis indicates that 3D printing is enabling orthodontic practices to move beyond conventional, laboratory-dependent processes toward digitally integrated, repeatable, and increasingly in-office workflows. The expansion of direct 3D printing for clear aligners, retainers, brackets, and fixed appliances is strengthening workflow efficiency, treatment customization, and same-day service capabilities, supporting the broader transition toward digitally enabled orthodontic care .

Investment Opportunities

Where Are Capital Inflows Concentrating in the Orthodontics Market ?

Capital is concentrating in expanded clinical indication development and digital scanning infrastructure, reflected in Align Technology's continued iTero Lumina adoption , representing approximately 86% of full systems units sold in the fourth quarter of 2025. This sustained scanner and software investment signals durable capital allocation toward integrated digital platform differentiation across the industry.

How Is Infrastructure Investment Shaping Long-Term Capacity?

Our findings suggest that infrastructure investment is shifting toward direct 3D printing manufacturing capacity that compresses aligner and appliance production timelines relative to traditional thermoforming methods. This shift favors manufacturers with existing digital manufacturing infrastructure that can scale alongside rising clear aligner case volume across both branded and private label commercial models.

What ESG Considerations Are Influencing Investment Decisions?

Environmental, Social, and Governance considerations in this market center on expanding orthodontic care access in underserved regions and responsible direct-to-consumer treatment oversight, given documented safety and oversight concerns around unsupervised aligner treatment. We found that investors increasingly favor companies demonstrating expanded access to trained-doctor-supervised treatment alongside transparent remote monitoring safety protocols.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

Industry leaders gain segment-level revenue forecasts and CAGR benchmarks across offering, customer type, and patient cohort axes, enabling product-roadmap decisions grounded in the same 2025–2035 figures used consistently throughout this analysis. Our findings on regional growth differentials further support market-entry and DSO-partnership strategy decisions.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a reconciled market-sizing model, competitive-landscape assessment, and named-company development tracking that supports valuation and capital-allocation decisions. The report's Growth Catalyst & Risk Assessment Matrix quantifies driver and restraint impact on CAGR, aiding scenario analysis for portfolio positioning.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain visibility into which offering and customer-type segments, such as Orthodontic Digital Solutions and Direct Consumer, are growing fastest, informing where to prioritize engineering investment and go-to-market focus through 2035.

Key Market Segments Evaluated

By Offering

  • Orthodontic Products
  • Orthodontic Digital Solutions
  • Orthodontic Services

By Customer Type

  • Orthodontist
  • General Dentist
  • Dental Service Organization
  • Clinic and Hospital
  • Dental Laboratory
  • Direct Consumer

By Patient Cohort

  • Adult
  • Teen
  • Child

By Sales Channel

  • Direct Sales
  • Distributor Channel
  • E-Commerce Channel
  • Laboratory Channel
  • Direct to Consumer Platform

By Commercial Model

  • Branded Model
  • OEM Model
  • Private Label Model

By Treatment Stage

  • Diagnosis and Planning
  • Active Treatment
  • Retention Stage

By Manufacturing Technology

  • Thermoforming
  • Direct Printing
  • Conventional Manufacturing

By Region

North America: U.S., Canada, Mexico

Europe: UK, Germany, France, Italy, Spain, Sweden, Denmark, Finland, Netherlands, Rest of Europe

Asia-Pacific: China, India, Japan, South Korea, Taiwan, Indonesia, Vietnam, Australia, Philippines, Malaysia, Rest of APAC

Middle East & Africa: Saudi Arabia, UAE, Egypt, Israel, Turkey, Nigeria, South Africa, Rest of MEA

Latin America: Brazil, Argentina, Chile, Colombia, Rest of LATAM

Conclusion & Recommendations

Our assessment indicates that manufacturers should prioritize expanded clinical indication development and DSO-focused digital bundling to capture the fastest-growing Orthodontic Digital Solutions and Dental Service Organization segments. Companies without established digital ecosystem capability should pursue platform partnerships rather than standalone product strategies given the market's clear shift toward integrated workflow solutions.

How Attractive Is the Orthodontics Market for Investment?

Investment attractiveness is high in Asia-Pacific and Latin America given superior CAGR profiles of 13.18% and 12.93% , respectively, while North America offers the largest absolute revenue base with strong DSO-driven recurring demand. We found that digital solutions and services revenue streams offer stronger margin and growth profiles than mature physical product segments alone.

What Are the Key Market Shifts and Risks?

Key risks include high out-of-pocket treatment costs constraining adoption in price-sensitive emerging markets and direct-to-consumer aligner safety and oversight concerns drawing regulatory scrutiny in developed markets. Our analysis shows that companies unable to demonstrate safe, supervised treatment protocols risk facing tightening oversight that could slow direct consumer channel growth specifically.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include expanded clear aligner clinical indications, deeper DSO-focused digital platform bundling, and teledentistry-enabled direct consumer models serving underserved access markets. We observed that companies combining all three pathways are best positioned to capture disproportionate share of the USD 43.57 Billion absolute opportunity created between 2026 and 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market & Revenue Analysis
  • Historical orthodontic revenue and shipment-volume analysis by offering, patient cohort, and sales channel, using company filings and dental association data.
  • Identifies high-growth offerings and patient cohorts to prioritize for investment.
Company-Level Product Share Analysis
  • Company-level share benchmarking across braces, clear aligners, retainers, and orthodontic accessories, based on disclosed segment revenue and case or unit data.
  • Shows competitive positioning and portfolio gaps against leading orthodontic suppliers.
Country-Level Trade Assessment
  • Country-wise import and export analysis for orthodontic appliances, wires, brackets, and related materials using UN Comtrade and customs data.
  • Supports sourcing, distribution, and localization decisions by revealing key supply and demand corridors.
Clear Aligner Case Volume & Manufacturing Technology Benchmarking
  • Benchmarking of aligner and appliance providers by case volume, 3D printing versus thermoforming and traditional manufacturing technology, and disclosed in-house versus outsourced production.
  • Guides manufacturing technology investment, capacity planning, and partnership decisions.
Customer Type & Commercial Model Assessment
  • Mapping of orthodontic demand across orthodontists, general dentists, DSOs, and clinics by commercial model, such as direct-to-consumer, doctor-led, and subscription or bundled treatment programs.
  • Pinpoints the most profitable customer segments and commercial models for go-to-market strategy.
Treatment Stage & Patient Cohort Opportunity Analysis
  • Analysis of product and service demand across treatment stages (diagnosis, active treatment, refinement, retention) for adolescent, adult, and pediatric cohorts, using public epidemiology and malocclusion prevalence data.
  • Reveals recurring-revenue opportunities, such as retainers and refinements, and priority patient cohorts for targeting.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖