Sweden Agriculture Robots Market By Type (Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots and Others), By Farming Type (Indoor Farming, Outdoor Farming and Indoor & Outdoor), and By Application (Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management and Others): Opportunity Analysis & Industry Forecast, 2025–2035
Industry: Agriculture | Latest Edition: August 20, 2026 | No of Pages: 175 | No. of Tables: 66 | No. of Figures: 60 | Format: PDF | Report Code: AG560
Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 206.04 Million |
|
Market Size in 2026 |
USD 258.61 Million |
|
Revenue Forecast in 2035 |
USD 782.01 Million |
|
Growth Rate |
CAGR of 13.08% from 2026 to 2035 |
|
Market Volume in 2025 |
1 Thousand Units |
|
Market Volume in 2026 |
2 Thousand Units |
|
Volume Forecast in 2035 |
10 Thousand Units |
|
Growth Rate |
CAGR of 19.46% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
14 |
|
Market Share |
Available for 10 Companies |
Industry Outlook
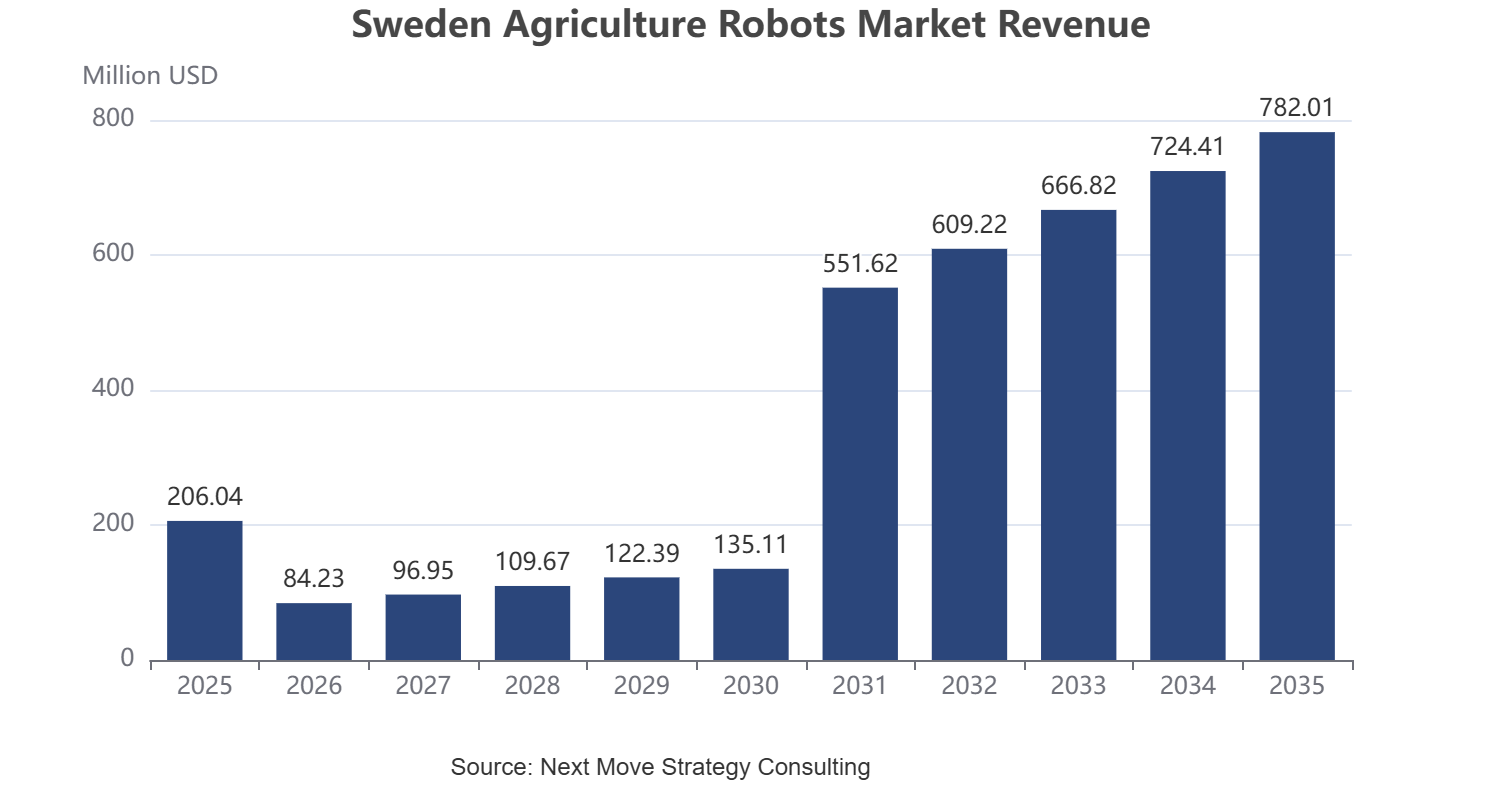
The Sweden Agriculture Robots Market was valued at USD 206.04 million in 2025, with market estimates reaching USD 258.61 million in 2026. Driven by increasing emphasis on sustainable agriculture, rising labor scarcity, and strong adoption of digital farming technologies, the market is projected to reach USD 782.01 million by 2035, advancing at a CAGR of 13.08% from 2026 to 2035. In volume terms, the market was estimated at 1 thousand units in 2025 and is projected to increase from 2 thousand units in 2026 to 10 thousand units by 2035, registering a CAGR of 19.46% during the forecast period.
Ecosystem Analysis of the Sweden Agriculture Robots Market
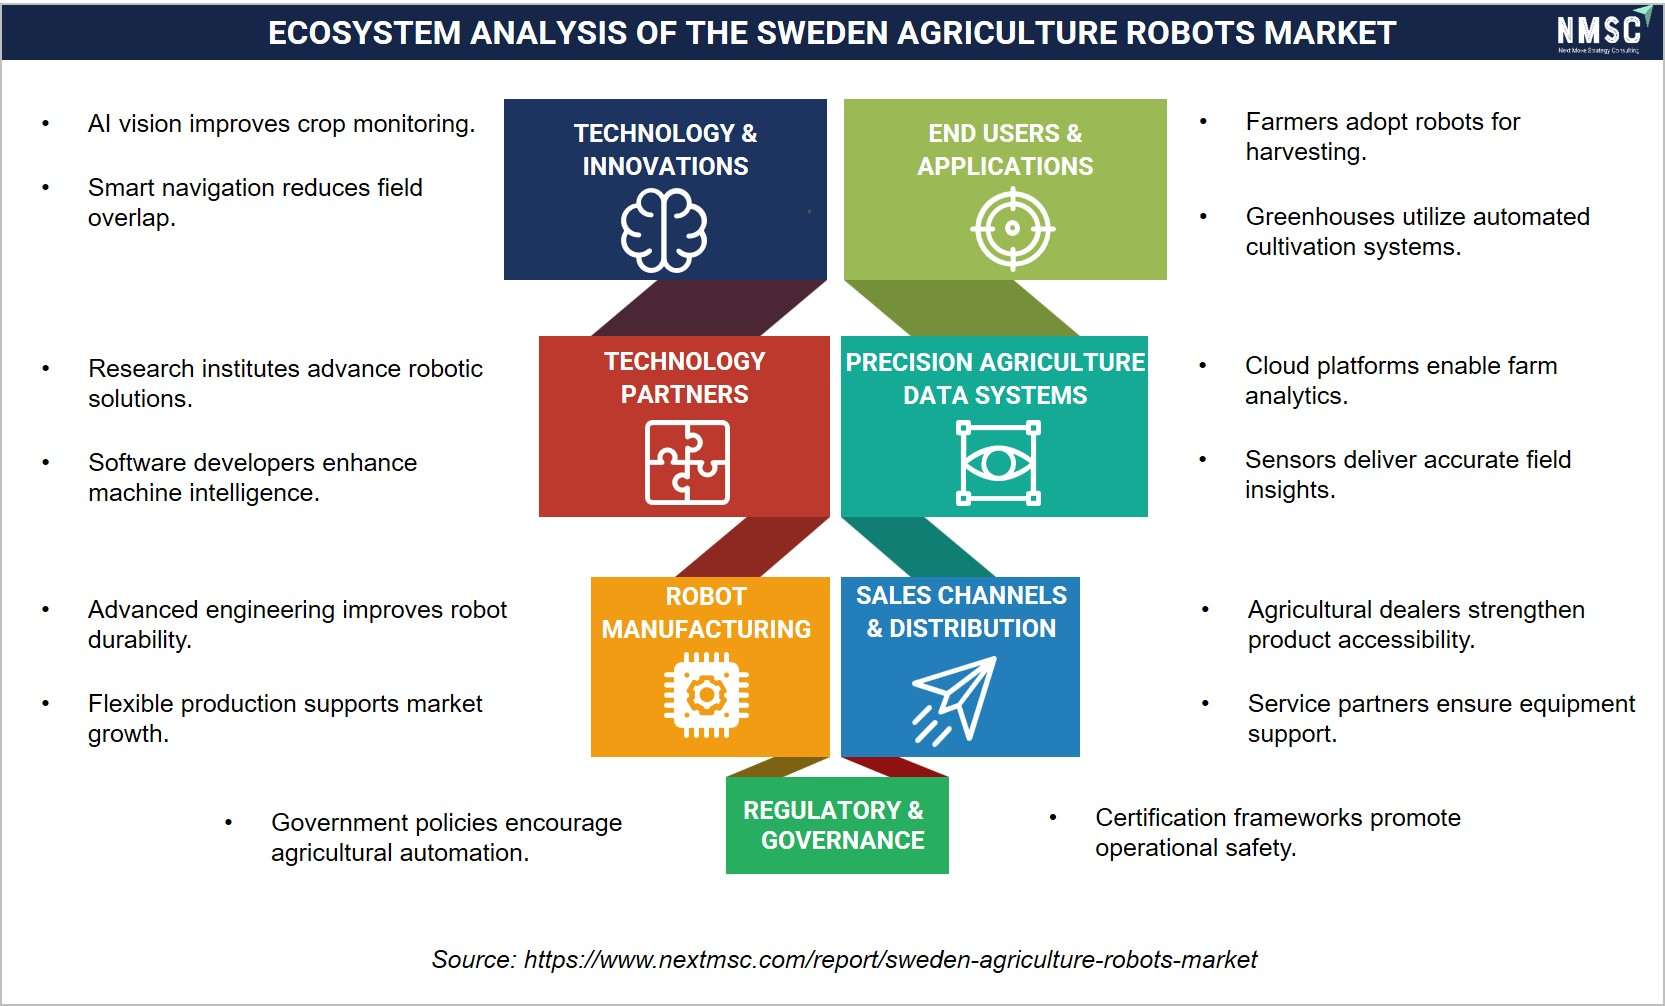
The ecosystem analysis highlights the interconnected stakeholders driving the Sweden Agriculture Robots Market, spanning technology innovators, robotics manufacturers, precision agriculture data providers, technology partners, distribution networks, end users, and regulatory authorities. It demonstrates how collaboration across the value chain accelerates innovation, supports efficient commercialization, enhances precision farming capabilities, and strengthens the adoption of autonomous agricultural solutions throughout Sweden.
What Are the Key Growth Catalysts, Inhibitors, and Opportunities Shaping the Sweden Agriculture Robots Market?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Increasing emphasis on sustainable agriculture is driving demand for precision robotic farming solutions. |
+2.10% |
Sweden |
Short to medium term (1–4 years) |
|
Rising labor scarcity is accelerating investments in autonomous agricultural equipment. |
+1.90% |
Sweden |
Short to medium term (1–4 years) |
|
Strong adoption of digital farming technologies is supporting agricultural robotics deployment. |
+1.70% |
Sweden |
Medium term (2–5 years) |
|
Significant capital requirements remain a challenge for small-scale farming operations. |
-1.40% |
Sweden |
Short to medium term (1–4 years) |
|
AI-enabled robotic crop management solutions present promising growth opportunities. |
+1.60% |
Sweden |
Medium to long term (3–7 years) |
The Sweden Agriculture Robots Market is shaped by a dynamic interplay of growth drivers, restraints, and opportunities that collectively define the competitive trajectory of the industry. Sweden's strong emphasis on sustainable agriculture, critical labor scarcity, and advanced digital farming ecosystems are primary forces driving market expansion. However, significant capital investment requirements continue to constrain adoption among smaller farming operations. Simultaneously, the emergence of AI-enabled robotic crop management solutions presents transformative market opportunities across diverse agricultural segments throughout the forecast period.
Growth Driver
How Is the Increasing Emphasis on Sustainable Agriculture Driving Demand for Precision Robotic Farming Solutions in Sweden?
Sweden's commitment to sustainable agricultural practices is creating compelling demand for precision robotic farming solutions that minimize environmental impact while maximizing productivity. Agricultural robots equipped with precision application technologies reduce chemical inputs, optimize resource utilization, and support carbon-neutral farming objectives. Swedish government sustainability mandates and green farming incentives are reinforcing this transition, encouraging farm operators to invest in robotic platforms that align with national environmental standards. This sustainability imperative is emerging as a fundamental market demand catalyst across the Sweden Agriculture Robots Market.
How Is Rising Labor Scarcity Accelerating Investments in Autonomous Agricultural Equipment Across Sweden?
The persistent scarcity of agricultural labor in Sweden has become a critical structural challenge driving accelerated investment in autonomous farming equipment. With Sweden's aging rural workforce and declining interest in manual farming among younger populations, farm operators are actively deploying autonomous systems to maintain operational continuity. Agricultural robots provide scalable, reliable alternatives to manual labor across planting, harvesting, milking, and monitoring operations. This growing labor gap continues to serve as a primary near-term demand driver for autonomous agricultural equipment throughout the forecast period.
How Is the Strong Adoption of Digital Farming Technologies Supporting Agricultural Robotics Deployment in Sweden?
Sweden's well-established digital infrastructure and high technology adoption rates among farming enterprises are creating a favorable environment for agricultural robotics deployment. The integration of IoT connectivity, precision GPS navigation, AI-powered analytics, and cloud-based farm management platforms with robotic systems is significantly enhancing their operational utility. Swedish farm operators are increasingly leveraging digital farming ecosystems to maximize the efficiency of robotic platforms across field operations, dairy automation, and crop monitoring activities. This technological convergence is reinforcing sustained demand for advanced agricultural robots across the Swedish market.
Growth Inhibitor:
How Do Significant Capital Requirements Remain a Challenge for Small-Scale Farming Operations Seeking to Adopt Agricultural Robots in Sweden?
Despite compelling operational and sustainability benefits, significant capital investment requirements continue to represent a formidable adoption barrier for small-scale farming operations in Sweden. The upfront costs associated with advanced robotic platforms, including procurement, installation, system integration, and ongoing maintenance, often exceed financial thresholds accessible to smaller enterprises. While government subsidy programs partially offset these costs, coverage remains insufficient to fully bridge the financial gap. This economic constraint limits market penetration among smaller farms, creating uneven technology adoption rates across Sweden's agricultural sector.
Growth Opportunity:
How Do AI-Enabled Robotic Crop Management Solutions Present Promising Growth Opportunities in the Sweden Agriculture Robots Market?
AI-enabled robotic crop management solutions represent a transformative growth opportunity within the Sweden Agriculture Robots Market, offering precision-driven automation across crop scouting, weed detection, targeted treatment application, and yield optimization. The integration of machine learning algorithms, computer vision, and advanced sensor technologies is enabling agricultural robots to perform increasingly complex crop management tasks with high accuracy and minimal human intervention. As Swedish farms seek to enhance productivity while meeting sustainability mandates, the deployment of AI-powered crop management robots is expected to generate substantial market expansion throughout the 2026–2035 forecast period.
How Is the Sweden Agriculture Robots Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Farming Type
Which Farming Type Is Driving the Greatest Revenue Growth across the Sweden Agriculture Robots Market?
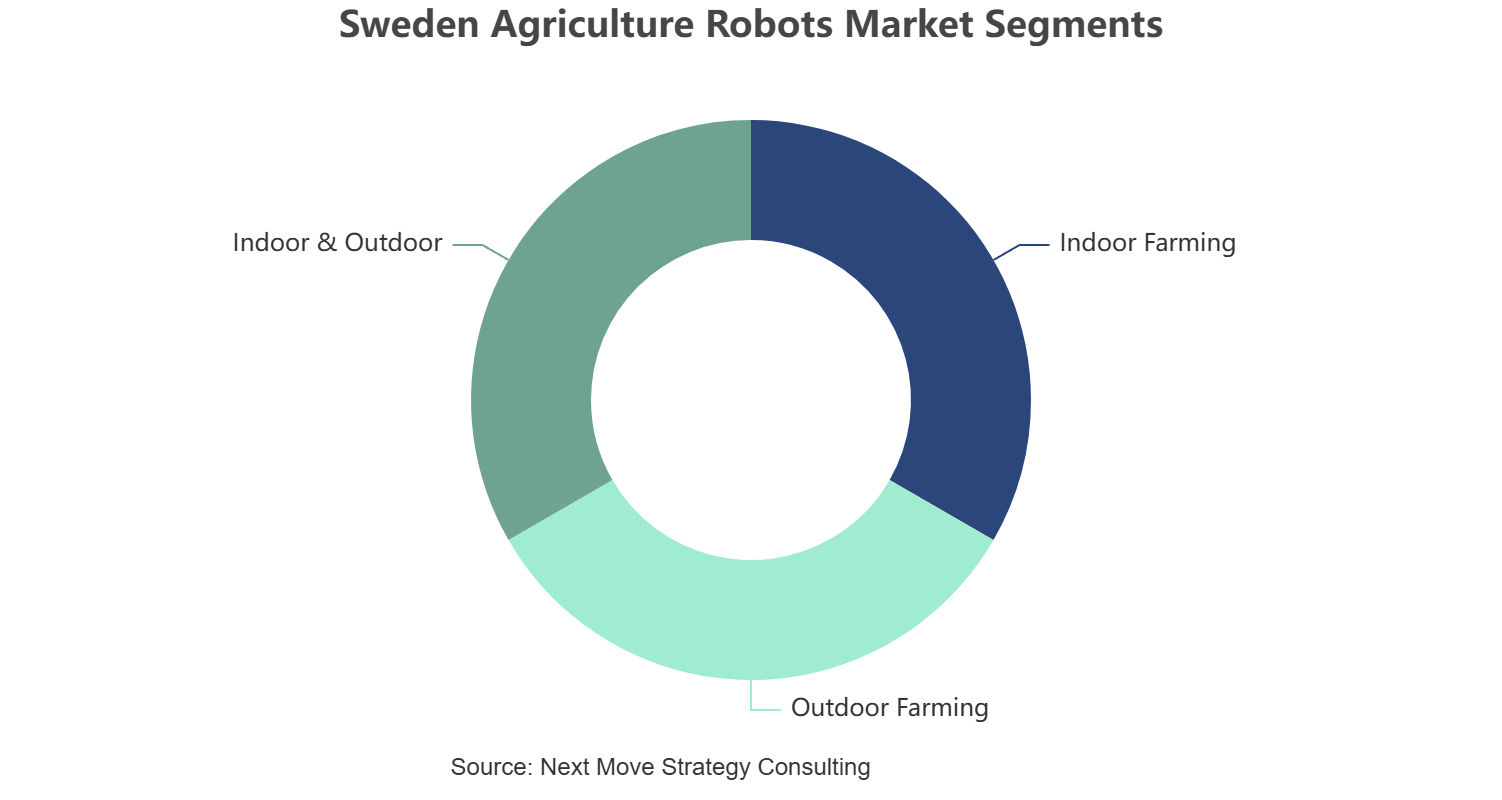
The Sweden Agriculture Robots Market by farming type is segmented into Indoor Farming, Outdoor Farming, and Indoor & Outdoor.
Among all farming types, Outdoor Farming accounts for the largest revenue share, supported by the widespread adoption of agricultural robots across Sweden's cereal farms, pasturelands, and dairy operations for autonomous field operations, precision spraying, crop monitoring, and forage management. Indoor Farming is witnessing steady growth as greenhouse cultivation increasingly adopts robotic automation to enhance productivity and resource efficiency. Meanwhile, the Indoor & Outdoor segment is gaining momentum as versatile robotic systems capable of operating across multiple farming environments improve operational flexibility and support sustained market growth throughout the forecast period.
By Application
Which Application Segment Holds the Largest Share of the Sweden Agriculture Robots Market Revenue?
By application, the Sweden Agriculture Robots Market is segmented into Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management, and Others.
Dairy & Livestock Automation holds a dominant position within the Sweden Agriculture Robots Market, driven by Sweden's well-established dairy industry and the widespread deployment of automated milking systems across the country's farming enterprises. Field Operations represents another significant segment, encompassing plowing, seeding, field farming, and soil and irrigation management activities that increasingly benefit from robotic automation. Aerial Monitoring & Scouting is experiencing robust growth through UAV-based crop protection and weather tracking capabilities. Harvest Management is emerging as a high-priority segment as labor shortages intensify demand for automated collection systems.
Key Segments
By Type
-
Unmanned Aerial Vehicles (UAVs)
-
Milking Robots
-
Driverless Tractors
-
Automated Harvest Robots
-
Others
By Farming Type
-
Indoor Farming
-
Outdoor Farming
-
Indoor & Outdoor
By Application
-
Aerial Monitoring & Scouting
-
Crop Protection & Weed Control
-
Crop Scouting & Monitoring
-
Weather Tracking
-
Inventory Management
-
-
Dairy & Livestock Automation
-
Milking
-
Dairy Management
-
Shepherding and Herding
-
-
Field Operations
-
Plowing
-
Seeding
-
Field Farming
-
Soil & Irrigation Management
-
-
Harvest Management
-
Others
Competitive Landscape
The Sweden Agriculture Robots Market features a highly competitive landscape characterized by a mix of established multinational corporations, specialized agri-tech innovators, and regional agricultural technology providers. Market participants are actively investing in research and development, strategic partnerships, and product diversification to strengthen their competitive positioning within the Swedish agricultural sector. The convergence of robotics, artificial intelligence, and precision agriculture is driving rapid product evolution, with companies competing on the basis of automation capabilities, energy efficiency, sustainability integration, and compatibility with existing farm management systems.
Key Players
-
DeLaval International AB
-
Lely Holding B.V.
-
Sveaverken Svea Agri AB
-
Homburg Holland B.V.
-
FarmDroid ApS
-
GEA Group AG
-
BouMatic LLC
-
Naiö Technologies SAS
-
SZ DJI Technology Co., Ltd.
-
Carbon Robotics, Inc.
-
Deere & Company
-
AGCO Corporation
-
CNH Industrial N.V.
-
CLAAS KGaA mbH
The competitive landscape of the Sweden Agriculture Robots Market features prominent players including DeLaval International AB and Lely Holding B.V., which lead dairy automation segments, alongside Sveaverken Svea Agri AB as a key regional participant. FarmDroid ApS specializes in precision seeding and weeding solutions, while GEA Group AG and BouMatic LLC compete in livestock automation. Naiö Technologies SAS and Carbon Robotics, Inc. advance precision crop management robotics, and SZ DJI Technology Co., Ltd. leads in UAV-based agricultural surveillance. Deere & Company, AGCO Corporation, CNH Industrial N.V., Homburg Holland B.V., and CLAAS KGaA mbH strengthen field operations automation capabilities across Sweden.
PESTEL Analysis of the Sweden Agriculture Robots Market
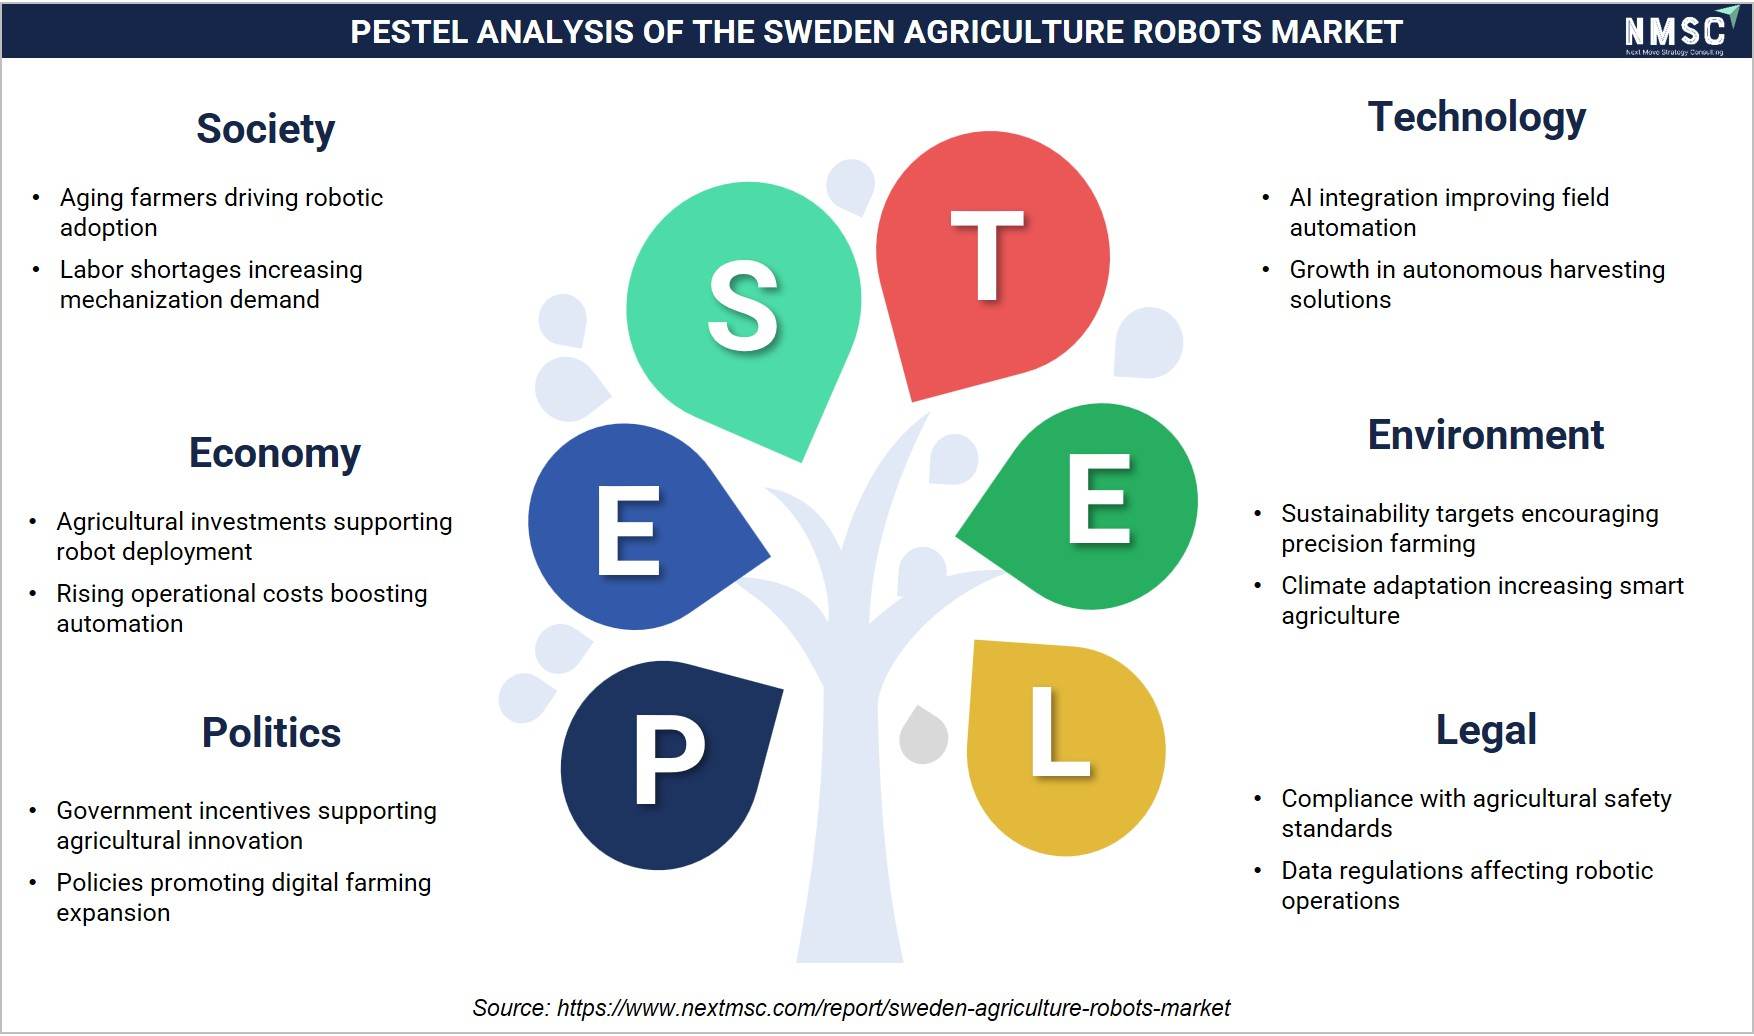
The PESTEL analysis evaluates the external factors influencing the Sweden Agriculture Robots Market, including government policies, labor dynamics, economic conditions, digital innovation, sustainability objectives, and regulatory standards. It illustrates how political, economic, social, technological, environmental, and legal developments collectively shape investment decisions, technology adoption, operational efficiency, and the long-term growth potential of agricultural robotics across Sweden.
Key Benefits for Stakeholders
This report delivers comprehensive market intelligence for stakeholders across the Sweden Agriculture Robots Market, enabling informed strategic decision-making. Industry participants, including manufacturers, technology developers, and agricultural enterprises, benefit from detailed segmentation analysis, competitive benchmarking, and growth opportunity identification. Investors and financial institutions gain access to rigorous market sizing and revenue forecasting data spanning the 2026–2035 forecast period, facilitating accurate investment evaluation and strategic portfolio management within the rapidly evolving Swedish agricultural robotics sector.
Policymakers and regulatory bodies can leverage the report's insights to develop evidence-based frameworks that support sustainable agricultural automation adoption across Sweden's farming sector. Research institutions and academic organizations benefit from the report's comprehensive analysis of market trends, innovation trajectories, and technology adoption patterns. The customizable nature of the report's segmentation structure enables stakeholders to tailor analytical outputs to specific regional, product, or application requirements, enhancing the relevance and applicability of market intelligence across diverse organizational contexts throughout the forecast period.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Sweden Agriculture Robots Market is poised for strong and sustained growth throughout the 2026–2035 forecast period, underpinned by national sustainability commitments, critical agricultural labor scarcity, and Sweden's advanced digital farming ecosystem. With revenue projected to grow from USD 258.61 million in 2026 to USD 782.01 million by 2035 at a CAGR of 13.08%, the market presents compelling opportunities across robotic platforms and agricultural applications. Competitive dynamics are intensifying as global and regional players expand their presence, positioning Sweden as a significant contributor to European agricultural robotics market growth.
About the Author
 Mihul Sharma
— Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

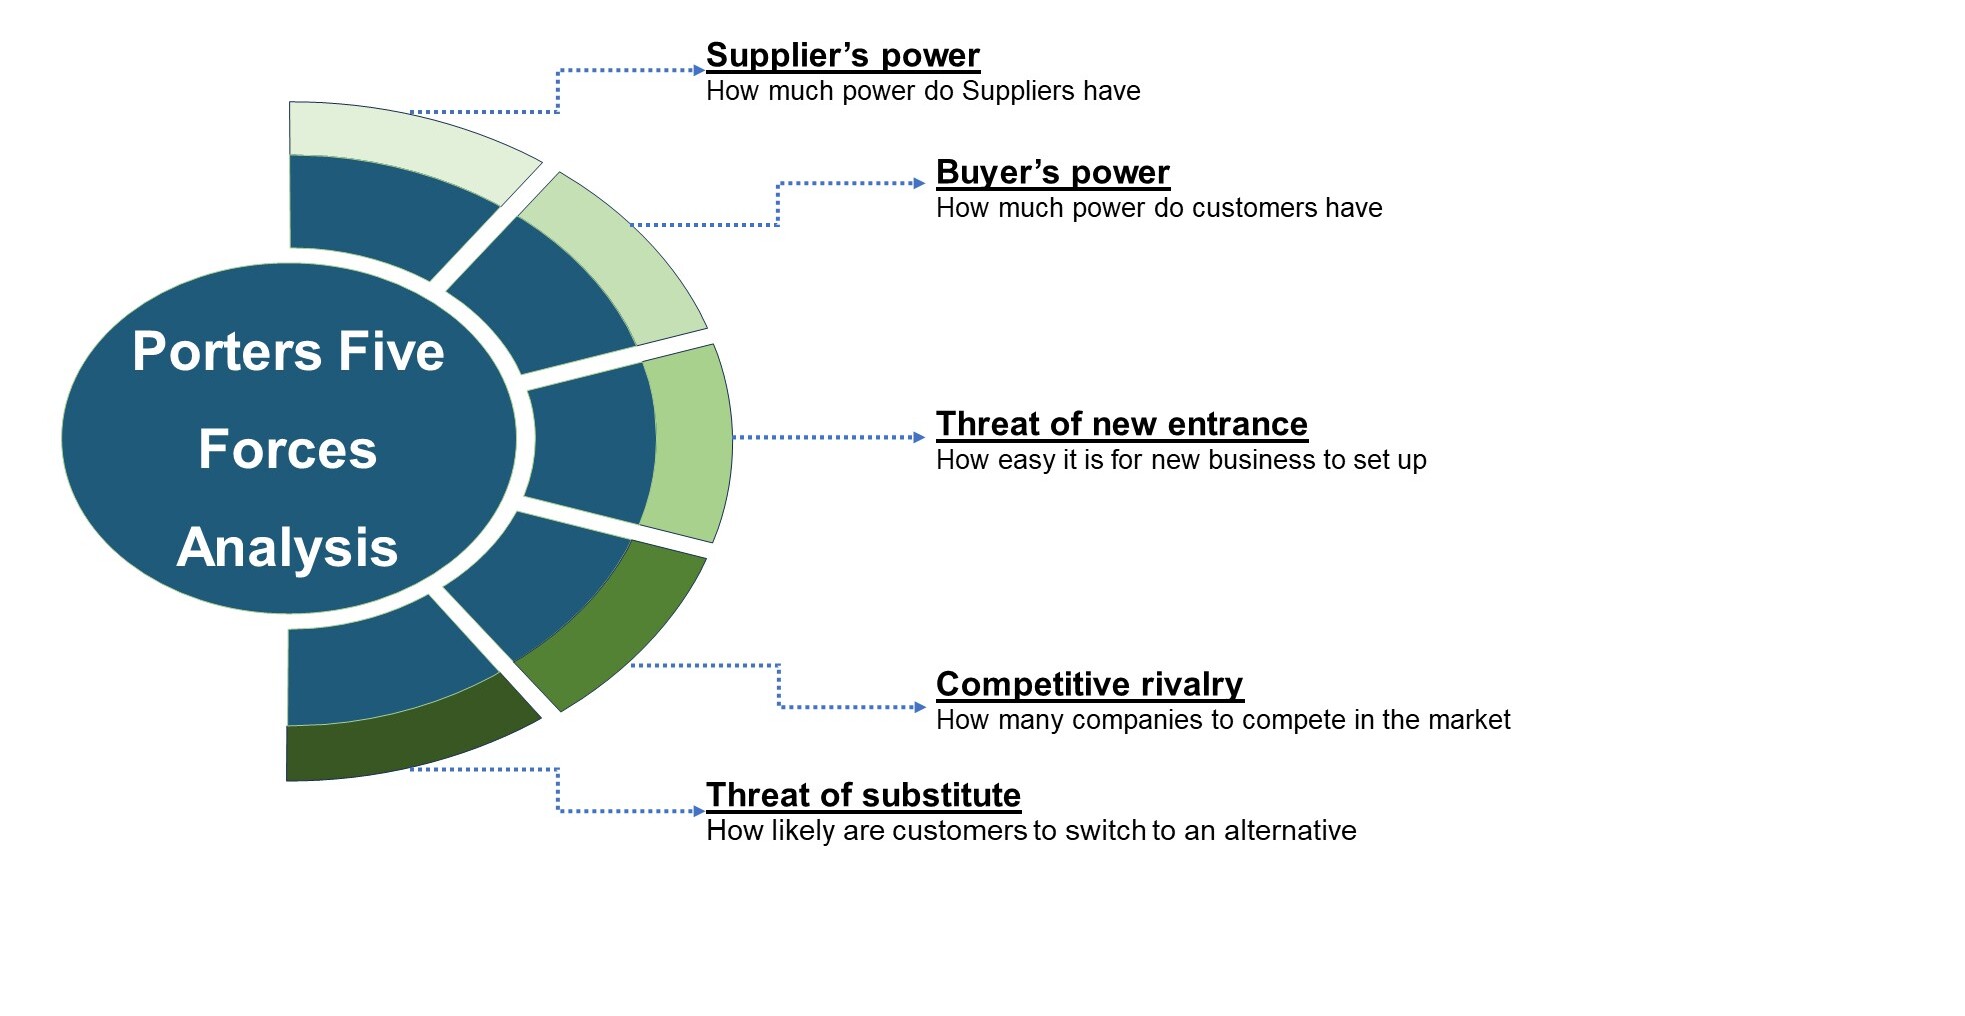
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.


 Speak to Our Analyst